

BUSINESS
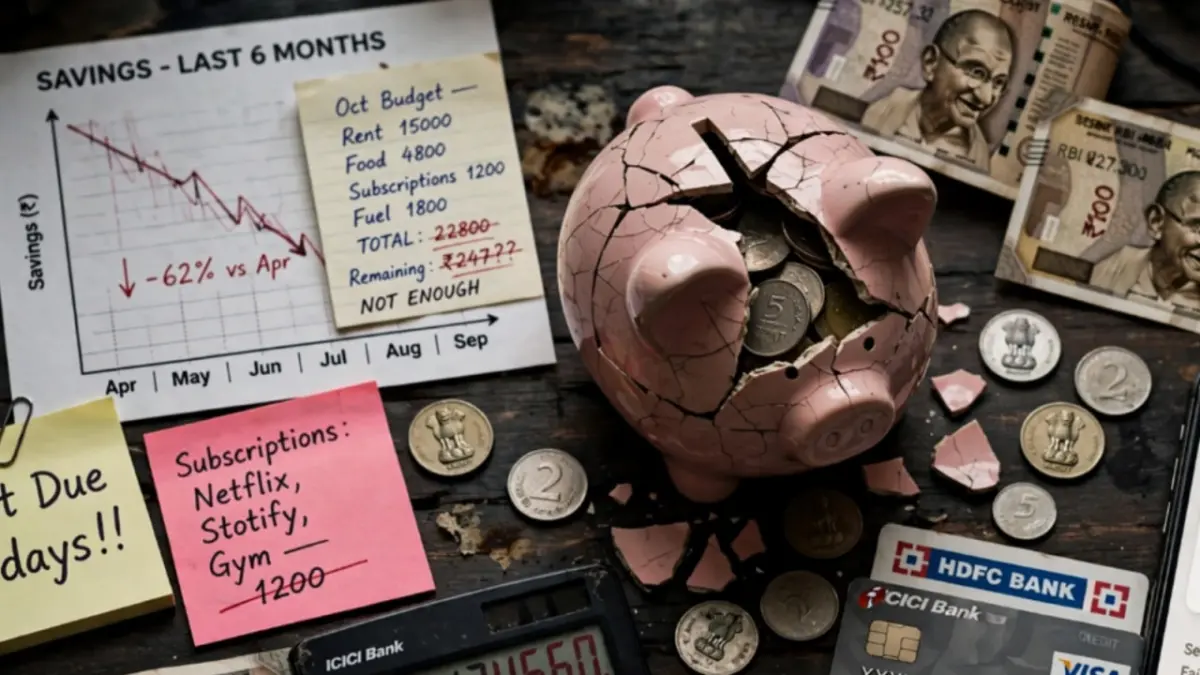
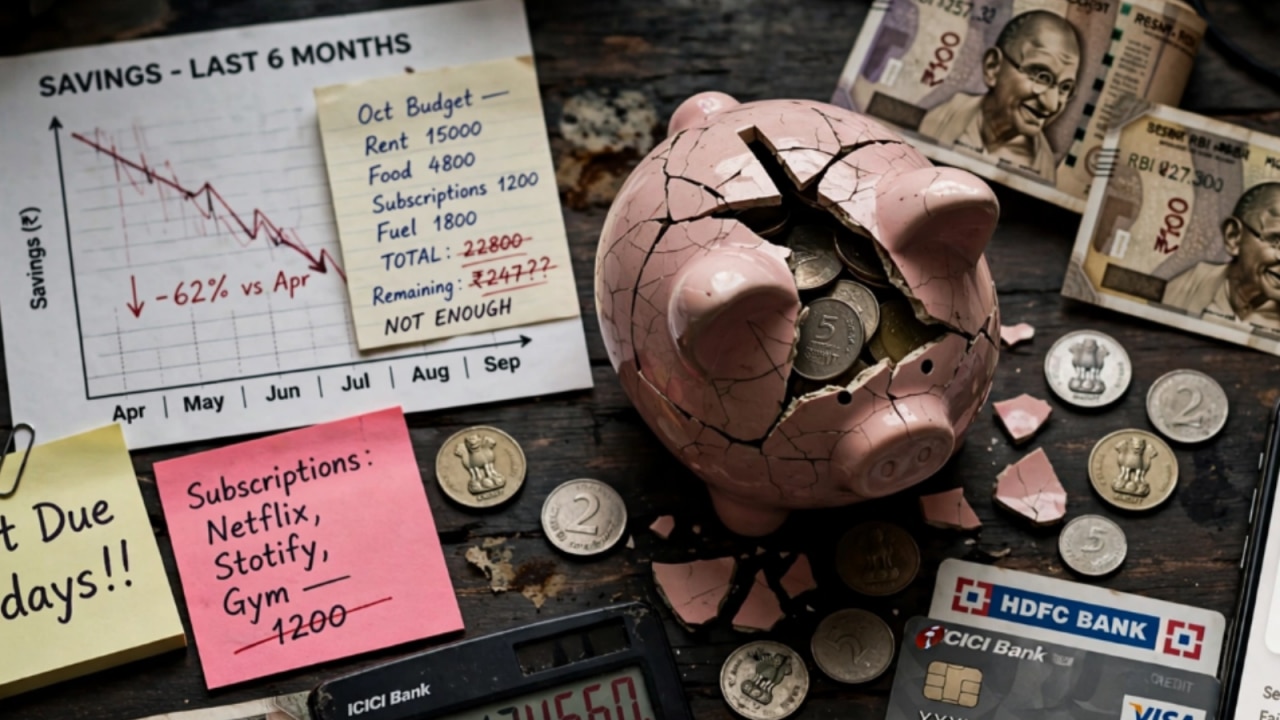
[Image: Gen Z Finance: From lifestyle spending, credit cards to financial planning—What experts suggest]
(AI-generated image)
Main Facts: A Generation at the Crossroads of Opportunity and Peril
India’s demographic dividend is significantly shaped by its burgeoning youth, with Generation Z rapidly integrating into the national workforce. By 2026, this cohort is projected to comprise a substantial 26% of the total workforce, according to the Great Place To Work India’s Great Mid-size Workplaces 2026 report. This marks a pivotal moment, as these young earners, often dubbed digital natives, are entering an economic landscape vastly different from their predecessors. They enjoy unprecedented access to digital payments, easily obtainable credit, and a diverse array of investment products, making both spending and investing seem more accessible than ever before.
However, this increased income and unparalleled access to financial tools have not automatically translated into robust financial security. A paradoxical situation is emerging where a generation with more financial options is simultaneously grappling with significant financial vulnerabilities. Experts across the financial spectrum are observing a troubling trend: common money mistakes, the insidious creep of lifestyle inflation, rising credit card debt, and often ill-informed investment decisions that collectively undermine their long-term financial well-being. This article delves into these critical aspects, dissecting the challenges faced by Gen Z and outlining the strategic guidance offered by financial planning professionals to steer them towards a path of lasting financial resilience.
Chronology: The Evolving Financial Landscape for Digital Natives
The financial journey of Gen Z unfolds against a backdrop of rapid technological advancement and shifting societal norms. Unlike previous generations who grew up with more traditional banking and investment avenues, Gen Z has been immersed in a world of instant gratification and seamless digital transactions from their formative years.
Early 2000s to Early 2010s: The Digital Foundation
Born roughly between the mid-1990s and the early 2010s, the oldest members of Gen Z entered adolescence and young adulthood as smartphones became ubiquitous and the internet transformed from a novelty to a necessity. This period saw the rise of e-commerce, digital wallets, and social media platforms, subtly shaping their consumption habits and expectations. The seeds of "buy now, pay later" (BNPL) services and instant credit approvals were also being sown, though not yet fully mainstream.
Mid-2010s: The Fintech Revolution and Workforce Entry
As the first wave of Gen Z began entering the workforce, particularly from the mid-2010s onwards, India witnessed an explosion in financial technology (fintech). The Unified Payments Interface (UPI) revolutionized digital payments, making transactions frictionless. Mobile banking apps became sophisticated, and online investment platforms democratized access to markets previously dominated by traditional brokers. This era also coincided with a period of significant economic growth in India, offering more employment opportunities and higher starting salaries for graduates compared to previous generations. The allure of quick wealth through stock market trading, often amplified by social media trends, also began to take hold.
Late 2010s to Early 2020s: Accelerated Access and Emerging Challenges
By the late 2010s and early 2020s, the digital financial ecosystem was fully mature. Credit cards became easier to acquire, often with pre-approved limits, and personal loans were just a few clicks away. Social media platforms evolved beyond mere connection tools, becoming powerful engines for consumerism, showcasing aspirational lifestyles that often required significant spending to emulate. This period saw a noticeable increase in discretionary spending among young professionals, driven by peer pressure and the desire to project a certain image online.
The COVID-19 pandemic, while a global disruptor, also paradoxically accelerated digital adoption in finance. Many who were hesitant to use online services were forced to embrace them, further embedding digital financial habits. Post-pandemic, as economies reopened, there was a surge in "revenge spending," contributing to lifestyle inflation. Simultaneously, the volatility in global markets, coupled with easy access to speculative instruments like cryptocurrencies and options trading, drew many young investors seeking rapid returns, often without a foundational understanding of risk management. This chronological progression highlights how Gen Z has been consistently exposed to an environment that simultaneously offers immense financial opportunity and significant pitfalls, making informed decision-making more crucial than ever.
Supporting Data: Unpacking the Financial Realities of Gen Z

The journey of Gen Z in India’s workforce, while marked by higher incomes and unprecedented access to financial products, is paradoxically shadowed by significant financial vulnerabilities. Data and expert observations paint a clear picture of common pitfalls, from unchecked spending to risky investment habits and mounting debt.
The Preparedness Paradox: Income vs. Security
Ramesh Vishwanathan, CEO of FPSB India, incisively highlights a critical disconnect: "Young earners today have access to financial information, credit, and investment options, but access does not automatically translate into financial preparedness. A common mistake is assuming that higher income means security." This statement underscores the core issue – a wealth of tools without the wisdom to wield them effectively. Vishwanathan further explains that as young earners’ salaries grow, a common pitfall is the parallel rise in lifestyle expenses, often leaving little room for crucial savings and future goal achievement. He advocates for a fundamental shift, suggesting that the starting point for financial resilience must be a clear understanding of cash flows, identification of priorities, and a deliberate effort to ensure that increasing income actively builds financial robustness rather than merely fueling current consumption.
Lifestyle Pressures and Spending Habits: A Deep Dive
The allure of an aspirational lifestyle, often amplified by social media, places immense pressure on Gen Z. This is clearly reflected in their spending patterns and their reported financial stress.

-
Deloitte’s 2026 India Gen Z and Millennial Survey provides stark figures:
- A significant 20% of Indian Gen Z respondents admit to struggling to pay their living expenses each month, indicating a constant battle with financial liquidity despite potentially higher incomes.
- More than half (54%) reported delaying major life decisions – such as marriage, buying a home, or having children – directly because of their precarious financial situation. This highlights how immediate financial struggles are impacting long-term life planning.
- Housing affordability emerged as a dominant concern, with over 60% of Gen Z and millennials stating it directly influences their career decisions, often compelling them to seek higher-paying jobs or specific locations, even if not ideal for personal growth.
-
SalarySe Data on UPI Transactions offers granular insights into where Gen Z’s money goes:
- An analysis of over 5.2 lakh salaried Gen Z users and millions of UPI transactions reveals that a substantial 20% of their spending is allocated to bills and subscriptions. This includes utility bills, streaming services, gym memberships, and various app subscriptions, which collectively can drain a significant portion of disposable income.
- Groceries account for 15.7% of spending, a basic necessity, but still a considerable chunk.
- Shopping, covering everything from fashion to electronics, makes up 11.9%.
- Travel, often seen as a status symbol and experience-driven expense, accounts for around 5%.
- Crucially, "discretionary spending" stands at a high 32% for both the 18-23 and 24-29 age groups. This category, encompassing dining out, entertainment, impulse purchases, and luxury items, is where lifestyle inflation truly manifests. It represents spending that, while enjoyable, is not essential and can easily spiral out of control if not budgeted.
The Debt Dilemma: Credit Cards and Instant Loans
The ease of accessing credit has become a double-edged sword for Gen Z. While offering convenience, it often leads to accumulating unsustainable debt.

- TransUnion CIBIL data (reported by Financial Express) paints a concerning picture of rising credit card debt:
- In March 2026, Gen Z accounted for a staggering 50% of new credit card holders in India, a significant jump from 43% just a year prior. This indicates a rapid uptake of credit products by this demographic.
- Alarmingly, nearly 28% of Gen Z first-time cardholders accumulated balances exceeding Rs 25,000 within just three months of receiving their first card. This rapid accumulation of debt, often on high-interest credit cards, can quickly become a burden.
- Furthermore, 69% of these new cardholders took on another credit product within a year, suggesting a pattern of relying on credit to manage expenses rather than building financial buffers.
- Separately, TransUnion CIBIL-FIDC data revealed that approximately 46% of credit originations to Gen Z borrowers in the first half of 2026 came from Non-Banking Financial Companies (NBFCs). NBFCs often cater to a wider risk profile and may have higher interest rates, potentially pushing young borrowers into more expensive debt.
Investing Trends and Common Mistakes: Chasing Returns, Ignoring Fundamentals
The allure of quick returns and market trends often overrides sound investment principles for many young earners.
-
Parul Maheshwari, a Certified Financial Planner, observes: "I have found Gen Z to lack patience, make ad hoc investment decisions and chase the best-performing asset class in the recent past for higher returns. This often reflects in their working life, where they tend to chase jobs quickly for money without considering the quality of the job or what they can learn." This highlights a broader trend of short-term thinking impacting both career and financial choices. The constant pursuit of the "next big thing" in investments, whether it’s a hot stock, crypto, or a specific fund, often leads to buying high and selling low, eroding capital rather than building it.
-
Deepak Keshri, Certified Financial Planner and expert with Capital Trust, corroborates this, emphasizing the lack of goal-based financial planning: "Today, barely 20% – 30% of young earners truly grasp goal-based investing—and even among them, many fall for short-term speculative trends like crypto, options, etc. The remaining 70% to 80% are trapped in a debt-fueled lifestyle, spending heavy chunks of their salaries on EMIs for depreciating assets like gadgets, luxury cars, and dining out under peer and social media pressure." Keshri’s observation points to a significant majority struggling with a consumption-driven debt cycle. He stresses that this debt-fueled lifestyle often leaves them without crucial emergency savings and under immense financial stress. "Most have zero emergency funds and depend entirely on basic corporate health insurance. When their salary disappears into credit card bills and EMIs on day one, mental stress inevitably follows—and this is precisely where professional, holistic financial coaching becomes non-negotiable," he adds.

Collectively, this data paints a vivid picture of Gen Z’s financial landscape. It’s a mix of everyday expenses, rising financial pressures from inflation and lifestyle demands, coupled with increasing debt and growing access to credit. These pressures, combined with short-term investment decisions and a tendency to follow market trends, create significant hurdles for young earners striving to balance current spending with long-term goals such as homeownership, building an emergency fund, and planning for a secure retirement.
Official Responses: Expert Strategies for Financial Resilience
Recognizing the multifaceted challenges confronting Gen Z, financial experts are offering comprehensive strategies focused on education, discipline, and long-term vision. Their advice transcends simple budgeting, advocating for a holistic approach to financial well-being.

Ramesh Vishwanathan, CEO, FPSB India: The Core Principles of Preparedness
Vishwanathan underscores that financial planning is not merely about accumulating wealth, but fundamentally "about creating clarity around where you stand, what matters to you and what you need to prepare for." He advocates for a foundation built on four critical pillars for Gen Z:
- Emergency Reserve: Establishing a robust emergency fund is paramount. This typically means setting aside 3-6 months’ worth of living expenses in an easily accessible, liquid account. This fund acts as a crucial buffer against unforeseen circumstances like job loss, medical emergencies, or unexpected repairs, preventing reliance on high-interest debt.
- Protection: Beyond basic corporate health insurance, Vishwanathan stresses the importance of comprehensive protection. This includes adequate health insurance coverage that accounts for potential out-of-pocket expenses, and potentially term life insurance, especially if one has dependents or outstanding liabilities. Disability insurance can also be vital to protect future income streams.
- Responsible Debt Management: While credit can be a useful tool, managing it responsibly is key. This involves understanding the difference between "good debt" (e.g., education loans, home loans that build equity) and "bad debt" (e.g., high-interest credit card debt, personal loans for depreciating assets). He advises prioritizing the repayment of high-interest debt and avoiding the trap of minimum payments.
- Clear Financial Goals: Vague aspirations lead to haphazard actions. Vishwanathan suggests defining clear, measurable, achievable, relevant, and time-bound (SMART) financial goals. Whether it’s buying a home in five years, funding higher education, or starting a business, specific goals provide direction and motivation for saving and investing.
He particularly stresses the importance of starting retirement planning early, acknowledging that inflation will significantly erode the purchasing power of future money, and financial responsibilities will evolve over a lifetime. Delaying retirement planning, even by a few years in one’s twenties, can cost millions in lost compounding returns. He also recommends aligning investments with financial priorities and goals, moving away from speculative, trend-driven choices. "Financial planning is an ongoing process of making informed decisions, preparing for uncertainty, and building financial confidence over time," he concludes, emphasizing its dynamic and continuous nature.
Parul Maheshwari, Certified Financial Planner: Cultivating Disciplined Habits
Maheshwari directly addresses the ingrained habit of "spending-before-saving" prevalent among Gen Z, urging a fundamental shift. Her practical advice focuses on cultivating disciplined financial habits:

- Prioritize Saving: She suggests reversing the conventional approach: "save at least 25-30% of what you earn every month and then spend." This "pay yourself first" strategy ensures that long-term goals are consistently funded before discretionary spending takes over. Automating these savings through recurring transfers to a separate account can significantly boost adherence.
- Increase SIP Investments with Income Growth: As income rises, Maheshwari advises proportionally increasing Systematic Investment Plan (SIP) contributions. This ensures that lifestyle creep doesn’t consume all additional income, allowing wealth accumulation to accelerate alongside career progression.
- Credit Cards as Tools, Not Income: Her strongest caution is regarding credit card usage. "Use a credit card as a payment tool—not extra income," she states emphatically. The convenience of credit cards should not be mistaken for an extension of one’s salary. "Pay the full outstanding amount every month and avoid revolving credit-card debt. This is a must for Gen Z." This prevents the accumulation of high-interest debt, which can quickly spiral out of control and severely impact credit scores.
Deepak Keshri, Certified Financial Planner: Holistic Coaching and Smart Choices
Deepak Keshri’s recommendations revolve around the critical need for professional guidance and informed decision-making:
- Embrace Goal-Based Investing: Moving beyond speculative trends, Keshri advocates for goal-based investing. This means every investment decision should be tied to a specific financial objective, whether it’s a down payment for a house, education, or retirement. This approach brings discipline and a clear purpose to investment choices.
- Seek Professional Financial Coaching: Given the complexity of financial markets and the pervasive influence of social media, Keshri asserts that professional, holistic financial coaching is "non-negotiable." A certified financial planner can help Gen Z navigate market volatility, create personalized financial plans, set realistic goals, and hold them accountable.
- Build Robust Emergency Funds: Re-emphasizing Vishwanathan’s point, Keshri stresses the dire consequences of having "zero emergency funds." He explains that relying solely on basic corporate health insurance is insufficient for comprehensive protection. A dedicated emergency fund is the first line of defense against financial shocks.
- Distinguish Assets: Appreciating vs. Depreciating: He advises against spending "heavy chunks of their salaries on EMIs for depreciating assets like gadgets, luxury cars, and dining out under peer and social media pressure." Instead, he urges Gen Z to differentiate between assets that appreciate in value over time (e.g., real estate, well-chosen investments) and those that depreciate rapidly (e.g., most consumer goods). Directing funds towards appreciating assets builds long-term wealth.
- Combat Lifestyle Inflation and Peer Pressure: Keshri highlights that the "debt-fueled lifestyle" driven by peer and social media pressure leads to significant mental stress. Learning to differentiate between needs and wants, resisting FOMO (Fear Of Missing Out), and practicing mindful spending are crucial for breaking this cycle.
In addition to these expert insights, it’s vital for Gen Z to embrace:
- Financial Literacy Education: Proactively learning about personal finance, even through online courses, books, or reputable financial news sources, can empower them to make better decisions.
- Budgeting Tools: Utilizing budgeting apps or simple spreadsheets to track income and expenses can provide crucial visibility into spending patterns and identify areas for optimization. The 50/30/20 rule (50% needs, 30% wants, 20% savings/debt repayment) can be a useful starting point.
- Diversification: For investments, the principle of diversification across different asset classes (equities, debt, gold, real estate) is essential to mitigate risk.
- Early & Consistent Investing: The power of compounding is a Gen Z’s greatest ally. Starting even with small amounts consistently and early can lead to substantial wealth over decades.
By internalizing and acting upon these expert recommendations, Gen Z can transform their financial trajectory, moving from a position of vulnerability to one of empowered financial confidence and security.

Implications: Shaping the Future of India’s Workforce and Economy
The financial habits and decisions of Gen Z carry profound implications, not just for their individual futures but for the broader Indian economy and society. The current trends, if left unaddressed, could lead to significant challenges while embracing expert advice promises a more robust and prosperous future.
Individual Implications:
For individual Gen Z members, the consequences of current financial trends are multifaceted:

- Increased Financial Stress and Mental Health Burden: The data points to significant financial struggle and stress. Living paycheck-to-paycheck, battling credit card debt, and lacking emergency funds contribute to chronic anxiety, affecting mental well-being, productivity, and overall quality of life. Deepak Keshri’s observation of "mental stress inevitably follows" when salaries disappear into EMIs highlights this direct link.
- Delayed Life Goals: The Deloitte survey explicitly states that 54% of Gen Z are delaying major life decisions due to financial situations. This means postponed homeownership, delayed marriages, starting families later, or even foregoing higher education or entrepreneurial ventures. Such delays can have ripple effects on personal fulfillment and societal demographic patterns.
- Reduced Retirement Security: A lack of early retirement planning, compounded by a reliance on short-term speculative investments, threatens the long-term financial independence of this generation. Without adequate savings and a disciplined investment strategy, many Gen Z individuals may find themselves financially insecure in their later years, potentially becoming a burden on social welfare systems or their families.
- Limited Wealth Creation: The cycle of high discretionary spending and accumulating debt for depreciating assets severely limits their ability to build substantial wealth. This means fewer opportunities for intergenerational wealth transfer and a slower pace of economic advancement for many families.
Economic Implications:
At a macroeconomic level, the financial behaviors of Gen Z have significant ramifications:
- Consumer Debt Crisis Potential: The rapid rise in credit card adoption and debt accumulation among Gen Z, particularly through NBFCs, raises concerns about a potential consumer debt crisis. If a significant portion of the workforce is burdened by high-interest debt, it could dampen overall consumer spending on essential goods and services, slow economic growth, and potentially destabilize financial institutions if default rates rise.
- Impact on Productivity: A financially stressed workforce is often a less productive one. Employees preoccupied with debt and financial insecurity may exhibit lower engagement, higher absenteeism, and reduced innovation, impacting corporate performance and national economic output.
- Shifting Spending Patterns: The observed high discretionary spending, particularly on lifestyle items, indicates a consumption-driven economy. While this fuels certain sectors, an overreliance on such spending at the expense of savings and long-term investments can create an unstable economic foundation, making the economy more susceptible to shocks.
- Capital Market Volatility: Gen Z’s tendency to chase speculative investments and market trends can contribute to increased volatility in capital markets. This behavior, driven by short-term gains rather than fundamental analysis, can create bubbles and subsequent crashes, impacting broader investor confidence and market stability.
Societal Implications:
Beyond individuals and the economy, the financial trajectory of Gen Z also has broader societal consequences:
- Widening Wealth Gap: If a significant portion of Gen Z struggles with debt and inadequate savings, while a smaller segment benefits from informed financial planning, it could exacerbate the existing wealth gap in India, leading to greater social inequality.
- Generational Financial Disparities: The financial struggles of Gen Z could create stark disparities between generations, with previous generations having potentially achieved greater financial security earlier in their lives. This could lead to intergenerational tension and a greater demand for social safety nets.
- Demand for Financial Education and Regulation: The challenges faced by Gen Z underscore the urgent need for enhanced financial literacy programs from an early age, potentially integrated into school curricula. There might also be increased calls for stricter regulations on easy credit access and predatory lending practices to protect vulnerable young consumers.
Call to Action and Future Outlook:
The current situation presents both a warning and an opportunity. While the data highlights significant vulnerabilities, the solutions offered by experts provide a clear roadmap for Gen Z to navigate these challenges. The urgent need for financial education, disciplined saving, responsible debt management, and goal-based investing cannot be overstated. Government bodies, educational institutions, financial service providers, and families all have a role to play in fostering a culture of financial literacy and responsibility.

Ultimately, with awareness, discipline, and access to professional guidance, India’s Gen Z has the potential to transform their financial narrative. By embracing proactive planning and making informed choices, they can move beyond the immediate pressures of lifestyle inflation and debt to build a robust foundation for long-term financial security, contributing positively to their personal well-being and the nation’s economic future. The paradox of opportunity and peril can indeed be resolved, paving the way for a generation that is not just financially aware, but truly financially resilient.
