
New Delhi, India – September 21, 2026 – Apple, the Cupertino-based technology behemoth, is reportedly poised to introduce its highly anticipated mobile payment service, Apple Pay, to the Indian market next month. This strategic move, confirmed by multiple reports from reputable sources like Reuters and Bloomberg’s Mark Gurman, signals a significant expansion of Apple’s footprint in one of the world’s fastest-growing digital economies. The launch is set to occur sometime in October 2026, marking Apple Pay’s debut in one of the few major global economies where it has not yet been available.
The timing of Apple Pay’s entry is particularly noteworthy, coinciding with a period of intense debate surrounding the Indian government’s controversial new 0.4 per cent UPI merchant fee on certain transactions. This regulatory shift has sparked discussions across the business landscape regarding its potential impact on merchants and the broader digital payments ecosystem. Apple Pay, which enables iPhone owners to make secure tap-and-pay purchases using tokenised card details, aims to carve out a niche in a market overwhelmingly dominated by the Unified Payments Interface (UPI).
India, with its colossal population of 1.4 billion people, a burgeoning middle class, and over 750 million smartphone users consuming cheap mobile data, represents a critical frontier for Apple. The company’s prior efforts in India have largely focused on expanding manufacturing capabilities and retail presence. With its smartphone market share having doubled to 8% since 2022, according to Counterpoint Research, India stands as one of Apple’s fastest-growing markets, making the launch of a key service like Apple Pay a logical, albeit challenging, next step.
The impending debut of Apple Pay in India is not merely about introducing a new payment method; it represents a comprehensive strategic play by Apple to deepen its integration into the daily lives of Indian consumers, boost its services revenue, and further solidify its hardware ecosystem. The service promises enhanced security and convenience, allowing users to make transactions without the need for physical cards or even opening separate payment applications, relying instead on the seamless integration within their Apple devices.
Apple’s Expanding India Narrative: A Strategic Chronology
Apple’s journey in India has been a carefully orchestrated progression, evolving from a nascent market presence to a strategic global hub for manufacturing and sales. The introduction of Apple Pay is the latest chapter in this unfolding narrative, reflecting both the maturity of the Indian market and Apple’s long-term vision.
Apple’s Growing Footprint in India
For years, India was primarily a sales market for Apple, with a relatively small but growing base of affluent consumers. However, in the last half-decade, this dynamic has shifted dramatically. Apple began seriously investing in local manufacturing, initially through partners like Foxconn and Wistron, to assemble iPhones in India. This move was driven by a desire to diversify its supply chain away from China, mitigate geopolitical risks, and qualify for government incentives under schemes like the Production-Linked Incentive (PLI) program, which aims to boost domestic manufacturing.
By 2026, a significant portion of iPhones sold globally are assembled in India, underscoring the country’s transformation into a crucial manufacturing base for the tech giant. This manufacturing push has been complemented by an aggressive retail expansion. After years of operating through third-party resellers, Apple opened its first two official retail stores in India – Apple BKC in Mumbai and Apple Saket in Delhi – in April 2023. These flagship stores were met with enthusiastic receptions, symbolizing Apple’s direct commitment to the Indian consumer.
This dual strategy of manufacturing and direct retail has been instrumental in Apple’s market share growth. From a relatively modest position, Apple’s share of India’s smartphone market has doubled to 8% since 2022, a remarkable achievement in a highly competitive market dominated by affordable Android devices. This growth, primarily driven by premium segment consumers, indicates a significant and expanding user base that is increasingly receptive to Apple’s ecosystem of products and services. The launch of Apple Pay is therefore a natural extension, aiming to capitalize on this expanding user base and integrate them further into the Apple ecosystem.
The Path to Digital Payments Adoption: India’s Regulatory Evolution
India’s digital payments landscape has undergone a revolutionary transformation over the past decade, driven by a combination of government initiatives, technological innovation, and widespread smartphone adoption. The catalyst for much of this transformation was the demonetization policy of 2016, which, despite its initial disruptions, significantly accelerated the adoption of digital transaction methods.
At the heart of India’s digital payments success story is the Unified Payments Interface (UPI). Launched in 2016 by the National Payments Corporation of India (NPCI), UPI is an instant real-time payment system that facilitates inter-bank peer-to-peer and person-to-merchant transactions. Its success stems from its simplicity (using a Virtual Payment Address or mobile number), interoperability across various apps and banks, and zero transaction fees for consumers. This has made UPI ubiquitous, from street vendors to large retail chains, fundamentally reshaping how Indians transact.
For Apple Pay to thrive in this environment, significant regulatory groundwork was necessary. A critical development came in 2025 when the Reserve Bank of India (RBI) introduced new rules allowing biometric authentication, such as fingerprint scanning or facial recognition, for digital payments. This regulatory amendment was crucial for Apple Pay’s functionality, as the service heavily relies on Face ID or Touch ID for approving in-person payments, as well as transactions on websites or within apps.
Prior to these new rules, authentication mechanisms employed by most Indian digital payments service providers were largely restricted to one-time passwords (OTPs) sent via text message. While secure, OTPs added an extra step and could sometimes be cumbersome. The RBI’s embrace of biometric authentication aligns India’s regulatory framework with global best practices for secure and convenient digital payments, directly paving the way for services like Apple Pay to operate seamlessly within the country’s financial ecosystem. This forward-thinking regulatory environment demonstrates India’s commitment to fostering innovation while maintaining robust security standards in its rapidly evolving digital financial sector.
Supporting Data & Deep Dive into Apple Pay Mechanics
Understanding Apple Pay’s operational mechanics, its initial partnerships, and the competitive landscape it enters is crucial to assessing its potential impact in India. The service brings a blend of advanced security features and user convenience, but it faces an established and fiercely competitive market.
How Apple Pay Works: Security and Convenience
Apple Pay fundamentally transforms how users conduct transactions by securely digitizing their payment cards. At its core, Apple Pay utilizes Near Field Communication (NFC) technology for in-store purchases and integrates directly into apps and websites. The process begins when a user adds their credit or debit card to the Apple Wallet app on their iPhone, Apple Watch, iPad, or Mac.
Crucially, when a card is added, the actual card number is not stored on the device, nor on Apple servers, nor is it shared with the merchant during a transaction. Instead, Apple Pay employs a sophisticated security feature called "tokenization." Each time a card is added, a unique Device Account Number is assigned, encrypted, and securely stored in a dedicated chip on the device called the Secure Element. When a payment is initiated, this Device Account Number, along with a dynamic, one-time security code (cryptogram), is transmitted to the payment terminal or online merchant. This ensures that even if transaction data is intercepted, the actual card details remain protected, significantly reducing the risk of fraud.
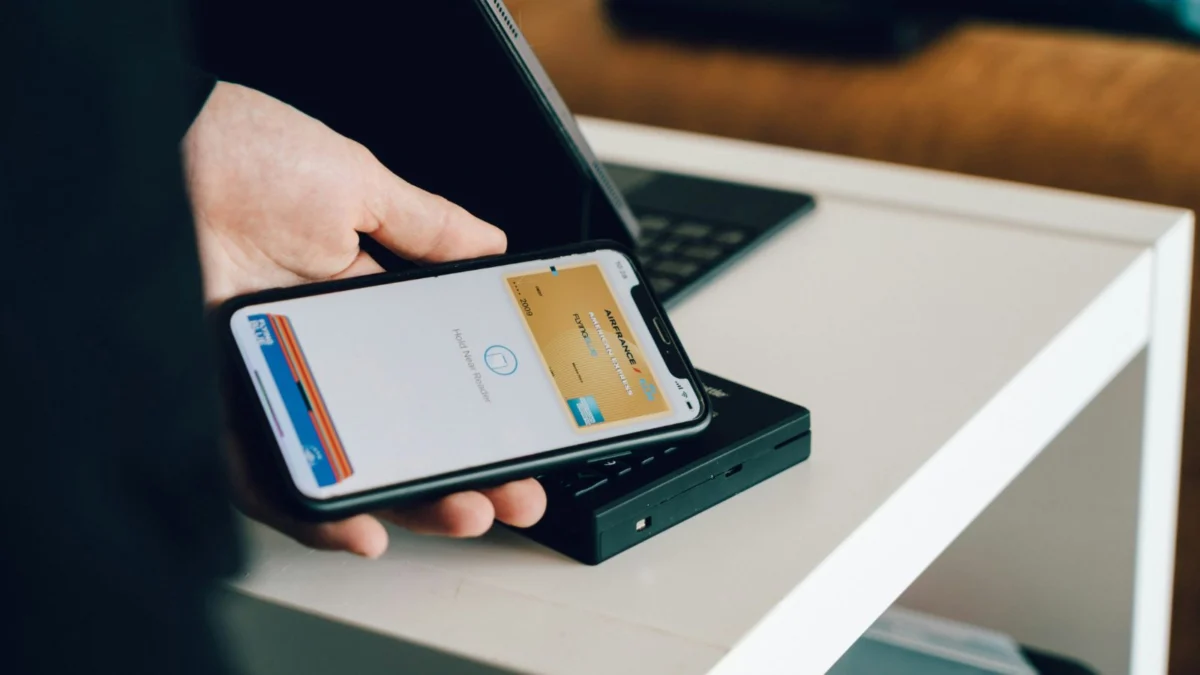
For in-store payments, the user experience is designed for speed and simplicity. On an iPhone, users typically double-click the side button (or home button for older models) to bring up their default card in Apple Wallet. Authentication is then performed using Face ID, Touch ID, or a device passcode. Once authenticated, the user simply holds the top of their device near the store’s contactless payment reader. On an Apple Watch, a similar double-click of the side button brings up the card, and the watch is then held to the reader. This entire process eliminates the need to carry physical cards, enter PINs, or sign receipts for smaller transactions, offering unparalleled convenience.
Multiple credit and debit cards can be added to the Apple Wallet, allowing users to select their preferred payment method before initiating a transaction. This multi-card support, combined with the robust security framework, positions Apple Pay as a premium, secure, and highly convenient payment solution for the modern consumer.
The Axis Bank Partnership and Future Expansion
The initial rollout of Apple Pay in India is reportedly set to commence with a partnership with Axis Bank for its credit cards. This is a significant first step for Apple, as Axis Bank is a prominent player in the Indian financial sector, ranking as the fourth-largest credit card issuer in the country. As of July 2026, Axis Bank reported 16.26 million active credit cards, making it a substantial base to launch the service.
This partnership means that iPhone and Apple Watch owners who are Axis Bank credit card holders will be among the first to experience Apple Pay’s tap-and-pay functionality. They will no longer need to physically present their cards, instead leveraging the secure digital wallet on their Apple devices.
Beyond Axis Bank, Apple is reportedly in discussions with other major lenders in India, including HDFC Bank and ICICI Bank. These two banks are Axis Bank’s largest private sector rivals and hold even larger market shares in terms of credit card issuance. HDFC Bank, SBI Cards, and ICICI Bank collectively lead the market, making their participation crucial for Apple Pay to achieve widespread adoption. The Reuters report indicates that while discussions are ongoing, commercial terms are yet to be finalized with these larger players.
The involvement of payment networks like Mastercard and Visa is also critical. Apple was previously reported to be discussing its plans with these global networks, as their infrastructure is essential for processing tokenized transactions. Securing partnerships with these major banks and payment networks is paramount for Apple Pay to expand its reach beyond the initial Axis Bank offering and integrate fully into the diverse Indian financial ecosystem.
India’s Digital Payments Landscape: A Formidable Challenge
Apple Pay enters a digital payments market in India that is not just competitive, but overwhelmingly dominated by the Unified Payments Interface (UPI). UPI currently accounts for an astounding 84% of India’s total digital payments volume, a testament to its widespread adoption and user-friendliness. This dominance presents both a challenge and a unique opportunity for Apple.
The competitive landscape is crowded with established global and homegrown players. Google Pay (GPay) and Walmart-backed PhonePe are the two dominant third-party UPI applications, commanding the largest share of UPI transactions. Other significant players include Amazon Pay, which leverages Amazon’s e-commerce ecosystem, and homegrown fintech giants like Paytm, which offers a comprehensive suite of payment and financial services. These platforms have invested heavily in merchant onboarding, consumer incentives, and user experience, creating deep roots across urban and rural India.
A critical point of speculation and potential strategy for Apple Pay in India is its possible support for UPI transactions. Earlier reports have suggested this integration, which would be a game-changer. If Apple Pay were to act as a front-end for UPI, allowing users to make UPI payments directly from their Apple Wallet using Face ID or Touch ID, it could significantly enhance its appeal. However, the exact mechanics of such an integration – whether Apple would build its own UPI stack or simply provide a secure wrapper around existing UPI functionalities – remain to be seen. Without UPI integration, Apple Pay’s reach would be limited primarily to credit/debit card transactions, catering to a smaller, albeit growing, segment of the market.
The recent 0.4% UPI merchant fee, introduced by the government on certain merchant transactions, adds another layer of complexity. While this fee is relatively small and primarily affects large merchants and specific transaction types, it has sparked debate over its impact on business costs and the broader adoption of digital payments. This could potentially make merchants more cautious about new payment solutions or encourage them to prioritize platforms that offer more favorable terms. Apple Pay will need to navigate this evolving regulatory and cost environment carefully to ensure widespread merchant acceptance.
Official Responses & Market Speculation
In the world of technology, major product or service launches are often preceded by a mix of official silence and fervent market speculation. Apple’s entry into India’s digital payments space is no exception, with key reports driving much of the anticipation.
Apple’s Silence and Market Anticipation
True to its corporate culture, Apple has maintained a characteristic silence regarding the impending launch of Apple Pay in India. The company rarely comments on future products or services until they are officially announced, preferring to control the narrative closely. This discretion often builds considerable anticipation among consumers, industry watchers, and investors alike.
The primary sources fueling the excitement are reports from highly respected financial news outlets. Reuters, known for its deep industry insights, and Bloomberg, particularly through the reporting of its seasoned Apple correspondent Mark Gurman, have consistently highlighted the imminent launch. These reports often cite anonymous sources close to the matter, including banking partners and individuals familiar with Apple’s internal plans. Their consistent reporting lends significant credibility to the October 2026 launch timeline.
Market analysts and technology pundits have been quick to weigh in on the potential impact. Many foresee Apple Pay catering initially to the premium segment of iPhone users who already embrace contactless payments and digital wallets. However, there’s also an understanding that for broader success, Apple Pay would need to address India’s unique payment habits, especially the dominance of UPI. The anticipation centers on whether Apple will tailor its service specifically for India, perhaps through UPI integration, or if it will rely on its global model of card-based transactions.
Banking Sector’s Viewpoint
From the banking sector’s perspective, the entry of Apple Pay is a double-edged sword. On one hand, it represents an opportunity to offer cutting-edge payment solutions to their premium customer base, potentially enhancing customer loyalty and attracting new cardholders. For Axis Bank, being the initial partner offers a first-mover advantage, positioning it as an innovative and technologically forward-thinking institution. This could be a result of more agile decision-making, favorable commercial terms agreed upon, or a strategic alignment with Apple’s vision.
On the other hand, for larger players like HDFC Bank and ICICI Bank, the reported delay in finalizing commercial terms suggests a more cautious approach. These banks already have established digital payment ecosystems and partnerships, often with Google Pay or PhonePe, and would need to carefully evaluate the financial implications, integration complexities, and strategic benefits of partnering with Apple. The revenue-sharing model that Apple typically employs for its payment services would be a key negotiation point, as banks would need to ensure a compelling return on investment and a clear competitive advantage.
Government and Regulatory Stance
The Indian government and the Reserve Bank of India (RBI) have been instrumental in fostering a robust digital payments ecosystem. Their stance has been one of encouraging innovation while ensuring financial stability, security, and consumer protection. The RBI’s 2025 rules allowing biometric authentication for digital payments clearly demonstrate a proactive approach to modernizing the payment infrastructure and making it conducive for advanced solutions like Apple Pay.
The government’s broader vision includes driving financial inclusion and reducing reliance on cash transactions. While UPI has been the primary vehicle for this, the entry of global players like Apple Pay aligns with the objective of offering diverse, secure, and convenient digital payment options to the populace. The government would likely view Apple Pay as a contributor to the overall digital payments volume, particularly in the card-based segment, which still holds significant value for high-value transactions. However, any solution would also need to respect data localization norms and comply with all Indian financial regulations, which are among the strictest globally.
Implications & Future Outlook
The launch of Apple Pay in India is more than just another service debut; it carries profound implications for Apple’s global strategy, the competitive dynamics of India’s digital payments market, and the future of consumer financial transactions in the country.
Impact on Apple’s Services Revenue
Apple has been aggressively diversifying its revenue streams beyond hardware sales, with services becoming an increasingly vital component of its financial performance. Apple Pay, globally, is a significant contributor to this services revenue, as Apple typically takes a small cut from each transaction processed through its platform. Given India’s vast population and its rapidly expanding digital payments market, the potential for Apple to grow its services revenue in the region is immense.
India’s market size offers an unprecedented opportunity to onboard millions of new users to Apple Pay. Even a small percentage of transactions from such a large base could translate into substantial earnings, contributing significantly to Apple’s overall services growth. This strategic move aligns with CEO Tim Cook’s vision of expanding Apple’s presence in emerging markets, not just through device sales but by integrating the company’s full ecosystem of services. The success of Apple Pay in India could serve as a blueprint for similar expansions in other high-growth, digital-first economies.
Hardware Ecosystem Synergy
Beyond services revenue, the introduction of Apple Pay in India is expected to create a powerful synergy within Apple’s hardware ecosystem. The feature is deeply embedded in Apple devices – iPhones, Apple Watches, iPads, and Macs – making these products even more attractive to consumers. The convenience and security offered by Apple Pay can become a compelling selling point, enhancing the value proposition of owning an Apple device.
For instance, an Apple Watch user can make payments directly from their wrist, while an iPhone user can seamlessly complete transactions with Face ID or Touch ID. This integration not only adds functionality but also reinforces customer lock-in within the Apple ecosystem. As more users adopt Apple Pay, it could potentially drive demand for new iPhones or Apple Watches, creating a virtuous cycle where services drive hardware sales, and hardware sales expand the services user base. This ecosystem stickiness is a cornerstone of Apple’s long-term strategy, ensuring that customers remain loyal to the brand and its interconnected suite of products and services.
The Battle for the Indian Digital Wallet
Apple Pay’s entry marks a new chapter in the intense battle for the Indian digital wallet. The challenges are formidable: overcoming UPI’s entrenched dominance, convincing merchants to adopt yet another payment system, and competing with established players who have spent years building their user bases and ecosystems.
Initially, Apple Pay might cater primarily to the premium segment of iPhone users and those who value its superior security and seamless experience. However, for broader success, Apple will need to address the mass market. The potential integration with UPI would be critical in this regard, allowing Apple Pay to tap into the vast network of UPI users and merchants. Without it, Apple Pay risks remaining a niche solution for card-based transactions.
The importance of merchant adoption cannot be overstated. While consumers might be keen on a new payment method, merchants need compelling reasons – such as low transaction costs, ease of integration, and a large user base – to accept it. The ongoing debate around the UPI merchant fee highlights the sensitivity of merchants to transaction costs. Apple Pay will need to offer competitive terms and demonstrate clear value to merchants to achieve ubiquitous acceptance.
In the long term, Apple Pay has the potential to carve out a significant niche, particularly among urban, tech-savvy consumers and in the premium retail segment. Its global brand recognition, coupled with the proven security and user experience of its platform, could enable it to attract a loyal user base. However, disrupting UPI’s dominance will be an uphill battle. More likely, Apple Pay will coexist with UPI and other digital payment platforms, contributing to the diversity and sophistication of India’s digital financial landscape.
Ultimately, India represents a crucial test and a massive opportunity for Apple Pay. Its success will not only bolster Apple’s services revenue and hardware sales but also provide valuable insights into adapting global payment solutions for highly dynamic and competitive emerging markets. As October 2026 approaches, all eyes will be on how Apple navigates this complex yet rewarding frontier.
