

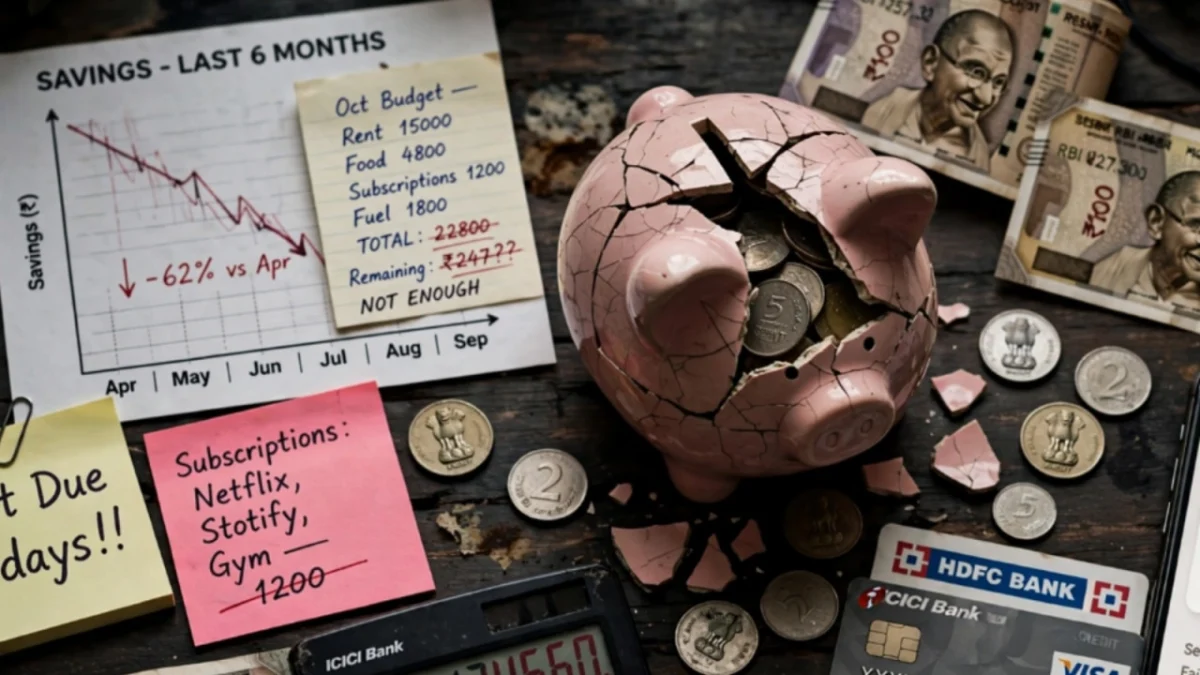
Mumbai, India – As India’s demographic dividend continues to mature, a new generation is rapidly reshaping the nation’s economic landscape. Gen Z, born roughly between 1997 and 2012, is not just joining the workforce; they are poised to become its dominant force. By 2026, this cohort is projected to comprise a significant 26% of India’s workforce, according to the latest Great Place To Work India’s Great Mid-size Workplaces 2026 report. This surge brings with it unprecedented opportunities, but also a complex array of financial challenges unique to their digital-native upbringing and the modern economic climate.
This generation, fluent in the language of digital payments, instant credit, and a vast universe of investment products accessible at their fingertips, finds itself at a peculiar crossroads. While the ease of spending and investing has never been greater, experts caution that this accessibility has not automatically translated into robust financial security. In fact, a growing body of evidence suggests that despite higher incomes and abundant financial tools, many young earners are struggling to build a stable financial future, grappling with lifestyle inflation, accumulating debt, and making impulsive investment decisions.
The Paradox of Prosperity: Access vs. Preparedness
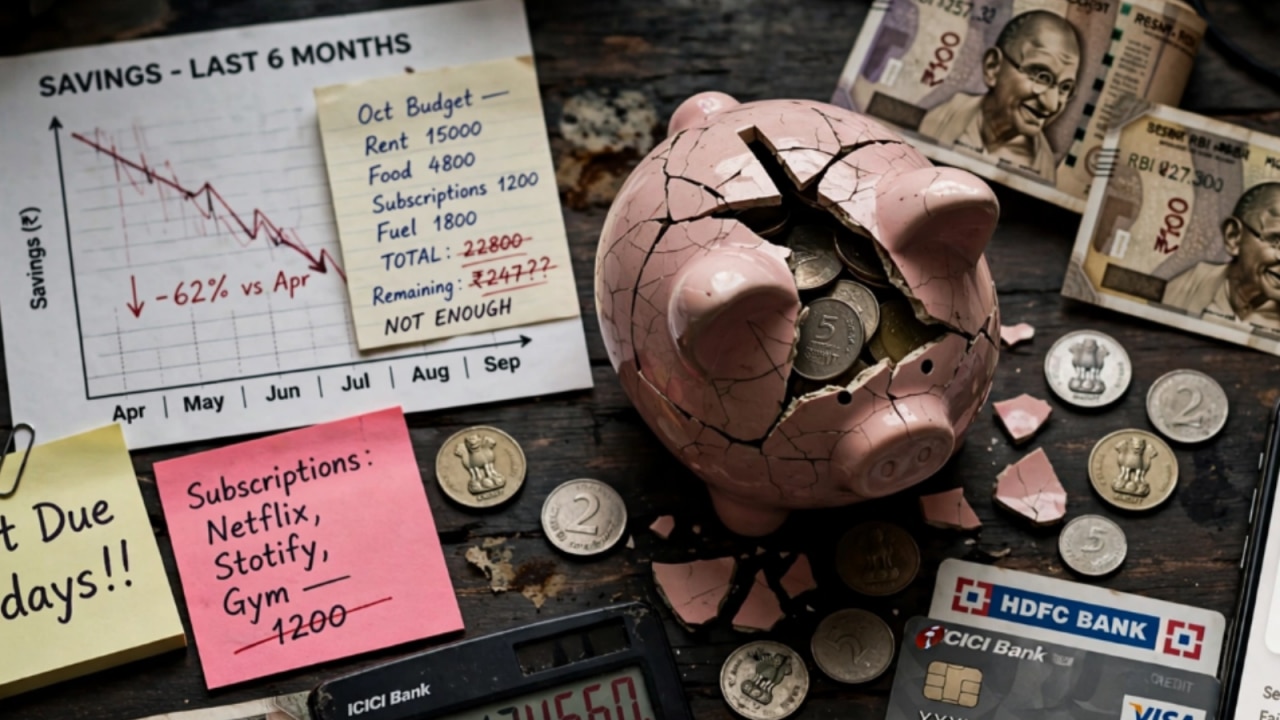
The prevailing narrative often links higher income with greater financial stability. However, for Gen Z, this correlation appears to be more nuanced. Ramesh Vishwanathan, CEO of FPSB India, incisively highlights this discrepancy: "Young earners today have access to financial information, credit, and investment options, but access does not automatically translate into financial preparedness. A common mistake is assuming that higher income means security." Vishwanathan’s observation underscores a critical educational and behavioral gap. While the tools are readily available, the wisdom and discipline to wield them effectively often lag.
As Gen Z’s salaries grow, a phenomenon Vishwanathan identifies as "lifestyle creep" or "lifestyle inflation" frequently takes hold. This involves an incremental increase in spending as income rises, often without a corresponding increase in savings or investment towards future goals. The insidious nature of lifestyle inflation means that despite earning more, individuals may find themselves with no greater discretionary income or savings buffer than when they earned less. "The starting point should be to understand cash flows, identify priorities and ensure that rising income also builds financial resilience," Vishwanathan advises, emphasizing the foundational importance of budgeting and goal-setting.
The Evolving Landscape of Gen Z’s Financial Footprint
The Workforce Ascent and Digital Embrace
Gen Z’s entry into the workforce coincides with an era of rapid technological advancement and economic transformation. They are digital natives, comfortable with online transactions, mobile banking, and instant gratification. This comfort, while enabling convenience, also blurs the lines between wants and needs, making impulse purchases easier than ever. Their professional lives are often characterized by a dynamic approach to careers, with a greater propensity for job-hopping in pursuit of better opportunities or higher salaries. While this agility can be advantageous, it can also disrupt long-term financial planning if not managed strategically.
Lifestyle Inflation: The Silent Eroder of Savings
The struggle to meet basic living expenses is a stark reality for a significant portion of Indian Gen Z. Deloitte’s 2026 India Gen Z and Millennial Survey revealed that a concerning 20% of Indian Gen Z respondents struggle monthly to cover their living costs. This financial strain has tangible repercussions on their life trajectories, with 54% admitting to delaying major life decisions—such as marriage, buying a home, or starting a family—due to their financial situation. Furthermore, the survey highlighted that housing affordability alone influences career decisions for over 60% of Gen Z and millennials, underscoring the immense pressure exerted by rising costs.
This generation is also navigating an economic climate marked by persistent inflation, which erodes purchasing power and makes saving for the future more challenging. The confluence of rising living costs, easy access to digital credit, and societal pressures to maintain a certain lifestyle creates a potent brew of financial stress. The ubiquitous presence of social media platforms further exacerbates this, as curated online personas often showcase aspirational lifestyles, fostering a sense of "keeping up with the Joneses" that can lead to overspending.
Spending Habits Under Scrutiny: Where Does the Money Go?
Data provides a revealing glimpse into Gen Z’s expenditure patterns. An analysis by SalarySe, based on insights from over 5.2 lakh salaried Gen Z users and millions of UPI transactions, paints a detailed picture. Young earners allocate a substantial 20% of their spending to bills and subscriptions—a reflection of the subscription economy and reliance on digital services. Groceries account for 15.7%, while shopping consumes 11.9% of their budget. Travel, a significant aspiration for many young individuals, accounts for around 5%. Critically, discretionary spending, which includes non-essential items and experiences, stands at a high 32% for both 18–23-year-olds and 24–29-year-olds. This large chunk of discretionary spending, while contributing to quality of life, often comes at the expense of crucial savings and investment.

The Allure and Peril of Easy Credit: A Deep Dive into Debt
One of the most concerning trends among Gen Z is their accelerating engagement with credit, particularly credit cards. TransUnion CIBIL data, reported by Financial Express, indicates a dramatic rise in Gen Z’s share of new credit card holders, soaring from 43% a year earlier to 50% in March 2026. This rapid adoption is not without its pitfalls. The report alarmingly noted that nearly 28% of Gen Z first-time cardholders accumulated balances exceeding Rs 25,000 within just three months of receiving their card. The propensity for quick credit accumulation extends beyond credit cards, with 69% of these new cardholders taking on another credit product within a year. Moreover, Non-Banking Financial Companies (NBFCs) are playing a significant role, originating approximately 46% of credit to Gen Z borrowers in the first half of 2026, as per TransUnion CIBIL-FIDC data.
Deepak Keshri, a Certified Financial Planner and expert with Capital Trust, points to a fundamental flaw in the financial approach of many young earners: a lack of goal-based financial planning. "Today, barely 20% – 30% of young earners truly grasp goal-based investing—and even among them, many fall for short-term speculative trends like crypto, options, etc.," Keshri explains. The vast majority, he contends, "are trapped in a debt-fueled lifestyle, spending heavy chunks of their salaries on EMIs for depreciating assets like gadgets, luxury cars, and dining out under peer and social media pressure."

This debt-fueled existence often leaves them perilously exposed. "Most have zero emergency funds and depend entirely on basic corporate health insurance," Keshri reveals, painting a grim picture of financial vulnerability. The cycle of salary disappearing into credit card bills and EMIs almost immediately after payday invariably leads to "mental stress," highlighting the profound link between financial health and overall well-being. Keshri emphatically states that in such a scenario, "professional, holistic financial coaching becomes non-negotiable."
Investment Trends: Chasing Returns in a Volatile Market
Beyond spending and debt, Gen Z’s approach to investing also raises concerns among financial experts. Parul Maheshwari, a Certified Financial Planner, observes a distinct behavioral pattern: "I have found Gen Z to lack patience, make ad hoc investment decisions and chase the best-performing asset class in the recent past for higher returns." This short-term, speculative mindset, driven by the desire for quick gains and influenced by online trends or ‘finfluencers’, often leads to suboptimal outcomes. Maheshwari draws a parallel between this investment behavior and their career choices: "This often reflects in their working life, where they tend to chase jobs quickly for money without considering the quality of the job or what they can learn." The pursuit of instant gratification, a hallmark of the digital age, appears to permeate both their professional and financial decisions, often at the expense of long-term stability and growth.

Expert Perspectives: Diagnosing the Challenges
The combined data and expert observations paint a clear picture: Gen Z’s financial landscape is characterized by a complex interplay of everyday expenses, escalating financial pressures, increasing debt, and easy access to credit. These pressures, coupled with a tendency towards short-term investment decisions and a susceptibility to market trends, significantly impede young earners’ ability to balance immediate gratification with crucial long-term objectives such as homeownership, building a robust emergency fund, and planning for retirement.
Ramesh Vishwanathan on Foundational Financial Resilience
Vishwanathan emphasizes that financial planning transcends mere wealth accumulation. "Financial planning is not about building wealth; it is about creating clarity around where you stand, what matters to you and what you need to prepare for." His advice for Gen Z centers on foundational preparedness: establishing an emergency reserve, securing adequate protection (like insurance), engaging in responsible debt management, and setting clear, actionable financial goals. He particularly stresses the critical importance of initiating retirement planning early, taking into account the corrosive effects of inflation and the inevitable evolution of financial responsibilities over a lifetime. Furthermore, he advocates for aligning investment strategies meticulously with individual financial priorities and goals, rather than chasing fleeting market trends. For Vishwanathan, "Financial planning is an ongoing process of making informed decisions, preparing for uncertainty, and building financial confidence over time."

Parul Maheshwari on Patience and Prudence in Investments
Maheshwari’s counsel is direct and actionable: Gen Z must fundamentally alter their "spending-before-saving approach." She strongly recommends a disciplined savings regimen, urging young professionals to "save at least 25-30% of what they earn every month and then spend." This ‘pay yourself first’ philosophy is a cornerstone of sound financial management. Regarding investments, she advises increasing SIP (Systematic Investment Plan) contributions in tandem with income growth, fostering a habit of consistent wealth creation. Crucially, she redefines the role of a credit card: "use a credit card as a payment tool—not extra income." Her imperative for Gen Z is unambiguous: "Pay the full outstanding amount every month and avoid revolving credit-card debt. This is a must for Gen Z." This discipline is vital to avoid the high-interest trap that can quickly derail financial progress.
Deepak Keshri on Goal-Based Planning and Debt Management
Keshri’s insights reinforce the necessity of structured financial planning, particularly in combating the debt-fueled lifestyle he observes. He advocates for a shift away from speculative investments towards a robust, goal-oriented approach. For those caught in the cycle of debt, Keshri’s advice on seeking "professional, holistic financial coaching" becomes paramount. Such coaching can provide the necessary framework to understand one’s financial situation, set realistic goals, create a budget, and develop strategies for debt reduction and wealth accumulation. He implicitly suggests that financial literacy is not merely about understanding products but about cultivating a disciplined mindset and strategic approach to money.

Broader Implications: A Generation at a Crossroads
The Socio-Economic Ripple Effect
The financial trends observed in Gen Z extend beyond individual struggles; they have broader socio-economic implications. A generation burdened by debt and lacking sufficient emergency savings is inherently less resilient to economic downturns, health crises, or job losses. This can lead to increased reliance on social safety nets, reduced consumer spending on non-essentials (once debt repayments consume disposable income), and a potential slowdown in capital formation. Their delayed entry into major life decisions, such as homeownership, can impact the housing market and related industries. Furthermore, a workforce constantly under financial stress may experience decreased productivity and increased mental health issues, affecting overall economic output and public health resources.
The Mental Toll of Financial Precarity
The link between financial stress and mental well-being is undeniable. For Gen Z, who are often more open about mental health challenges, financial precarity can be a significant contributor to anxiety, depression, and feelings of hopelessness. The constant pressure of debt, the struggle to meet basic expenses, and the perceived inability to achieve traditional markers of success can create a profound sense of inadequacy and stress. This mental burden can, in turn, affect their ability to perform at work, maintain relationships, and make sound financial decisions, creating a vicious cycle that is difficult to break without intervention. The emotional cost of a debt-fueled lifestyle and the absence of an emergency fund cannot be overstated.

Charting a Path Forward: Strategies for Financial Wellness
Given the complexities, a multi-pronged approach is essential to empower Gen Z towards financial wellness.
Cultivating a Savings-First Mindset
The foundational shift must be from "spend then save" to "save then spend." This involves:

- Automated Savings: Setting up automatic transfers from salary accounts to savings or investment accounts immediately upon receiving income.
- Budgeting Tools: Utilizing budgeting apps or spreadsheets to track income and expenses, identify spending leaks, and allocate funds purposefully.
- Emergency Fund: Prioritizing the creation of an emergency fund covering 3-6 months of living expenses, ensuring a safety net against unforeseen circumstances.
- Goal-Based Savings: Earmarking savings for specific short-term (e.g., travel) and long-term (e.g., down payment for a home) goals, making saving more tangible and motivating.
Responsible Credit Management
Credit cards, when used judiciously, can be beneficial, but their misuse is detrimental.
- Full Repayment: Always paying the entire credit card bill on time to avoid high-interest charges and maintain a healthy credit score.
- Credit as a Tool, Not Income: Understanding that credit is a loan, not an extension of income, and using it only for purchases that can be comfortably repaid.
- Monitoring Credit Score: Regularly checking credit reports and scores to ensure accuracy and understand one’s credit standing.
- Avoiding Multiple Debts: Being cautious about taking on too many credit products simultaneously, which can lead to unmanageable debt.
Strategic Investing for Long-Term Growth
Moving beyond speculative trends towards a disciplined investment strategy is crucial.

- Diversification: Investing across various asset classes (equities, debt, real estate, gold) to mitigate risk.
- Long-Term Perspective: Understanding that wealth creation is a marathon, not a sprint, and focusing on long-term growth rather than short-term gains.
- SIPs (Systematic Investment Plans): Regularly investing fixed amounts in mutual funds, leveraging rupee-cost averaging and compounding.
- Financial Education: Continuously educating oneself about different investment products, market dynamics, and personal finance principles.
- Retirement Planning: Starting early with retirement contributions, even small amounts, to harness the power of compounding over decades.
The Indispensable Role of Financial Education and Professional Guidance
The insights from experts like Vishwanathan, Maheshwari, and Keshri highlight a significant gap in financial literacy. There is a pressing need for:
- Early Financial Education: Integrating practical financial education into school and university curricula.
- Workplace Initiatives: Employers offering financial wellness programs and access to financial advisors.
- Government and Regulatory Support: Promoting responsible lending practices and consumer protection against predatory financial products.
- Professional Financial Coaching: Encouraging Gen Z to seek guidance from certified financial planners who can offer personalized, holistic advice tailored to their specific goals and circumstances. A professional can help them identify priorities, create a realistic budget, formulate an investment strategy, and navigate debt effectively.
In conclusion, Gen Z stands at a pivotal moment. Their entry into the workforce brings immense potential, but their financial journey is fraught with challenges amplified by the digital age and prevailing economic conditions. While access to financial products and information is unprecedented, the wisdom to manage these resources effectively is often lacking. By embracing disciplined savings, responsible credit management, strategic investing, and seeking professional guidance, this generation can transform their current struggles into a foundation for lasting financial security and prosperity, ensuring they are not just economically active, but financially resilient.

Find your daily dose of All Latest News including Sports News, Entertainment News, Lifestyle News, explainers & more. Stay updated, Stay informed- Follow DNA on WhatsApp.
