
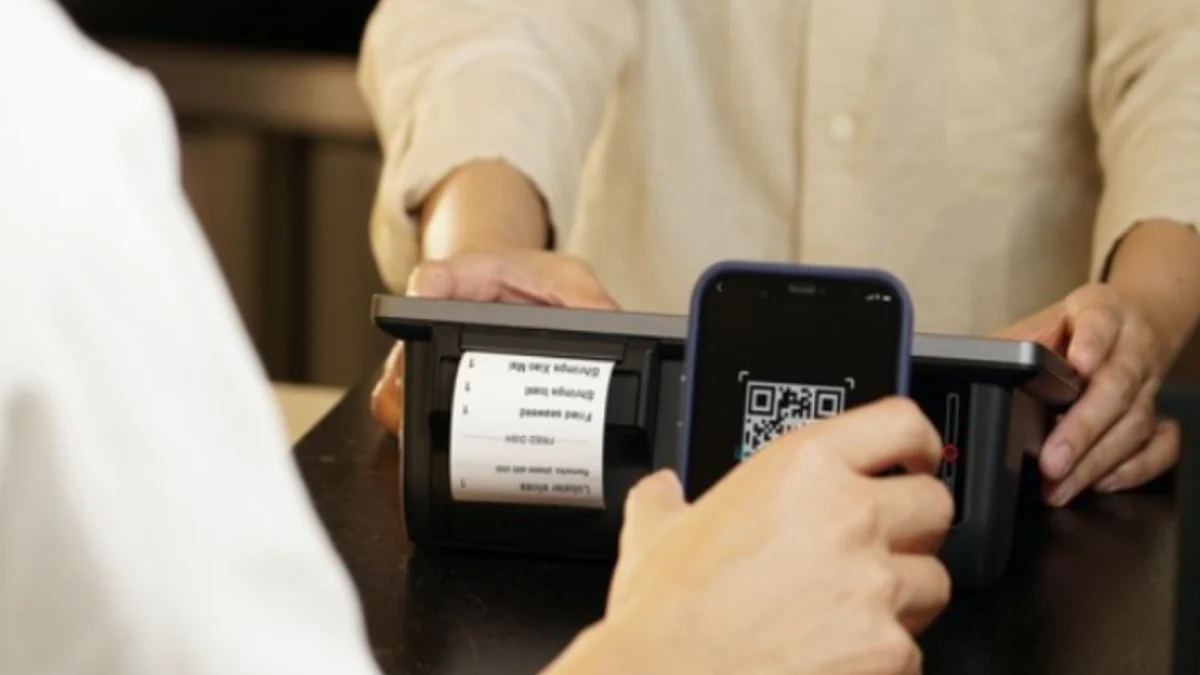
NEW DELHI, India – In a significant move aimed at further bolstering its burgeoning digital economy, the Indian government has officially mandated that banks and system providers are prohibited from imposing any charges on Unified Payments Interface (UPI) transactions up to a value of Rs 2,000, as well as on all payments made via RuPay debit cards. This directive, formalized through a gazette notification, reaffirms the Centre’s commitment to fostering a sustainable, competitive, and inclusive digital payment ecosystem, benefiting millions of consumers and small businesses across the nation.
The announcement puts to rest ongoing speculation regarding potential charges on UPI, particularly for smaller transactions, ensuring that one of India’s most revolutionary payment systems remains freely accessible for everyday use. The policy also extends to RuPay, India’s indigenous card network, reinforcing its position as a cost-effective alternative to international card schemes.
Main Facts: Government Solidifies Zero-Charge Policy for Digital Payments
The core of the government’s latest pronouncement is its unequivocal stance on transaction charges for specific digital payment modes. As per a recent gazette notification, the Central government has explicitly barred financial institutions and payment system operators from levying any direct or indirect fees on payments conducted via UPI for amounts up up to Rs 2,000, and all transactions made using RuPay-powered debit cards.
This crucial directive is rooted in Section 10A of the Payment and Settlement Systems Act, 2007 (Act No. 51 of 2007), which grants the government the authority to classify certain electronic payment modes and dictate their operational terms. The Ministry of Finance’s notification unequivocally states: "No bank or system provider shall impose, whether directly or indirectly, any charge upon a person making or receiving a payment by using the electronic modes of payment specified in the paragraph above."
The immediate impact of this ruling is profound. For millions of Indian citizens and small merchants, everyday transactions – from purchasing groceries and paying for transport to small retail purchases – will continue to be processed without any additional cost. This not only encourages wider adoption of digital payments but also reduces the financial burden on individuals and micro-enterprises, aligning with the government’s broader vision of a cashless and financially inclusive society. The decision underscores a strategic policy choice to prioritize accessibility and affordability over potential revenue generation from these specific transaction types, particularly given their high volume and low individual value.
Chronology: A Journey Towards a Cashless Economy
The government’s latest directive is not an isolated event but rather the culmination of years of strategic initiatives aimed at digitizing India’s economy and promoting financial inclusion. The journey began in earnest with the conceptualization and launch of UPI, a system designed to simplify and accelerate digital transactions.
The Genesis of UPI:
The Unified Payments Interface (UPI) was launched in 2016 by the National Payments Corporation of India (NPCI), an umbrella organization for operating retail payments and settlement systems in India, under the aegis of the Reserve Bank of India (RBI) and the Indian Banks’ Association (IBA). Its introduction marked a paradigm shift in India’s payment landscape, enabling instant real-time payments between bank accounts via a mobile platform. Unlike traditional bank transfers, UPI allowed users to link multiple bank accounts to a single mobile application, facilitating peer-to-peer (P2P) and person-to-merchant (P2M) transactions with unprecedented ease.
The Digital India Push:
The launch of UPI coincided with the government’s ambitious "Digital India" campaign, an initiative to transform India into a digitally empowered society and knowledge economy. Under this overarching vision, promoting digital payments became a cornerstone, seen as critical for transparency, efficiency, and reducing the dominance of cash. Early on, the government actively encouraged the adoption of UPI through various awareness campaigns and incentives.
RuPay’s Indigenous Rise:
Parallel to UPI’s growth, the government also championed RuPay, an Indian multinational financial services and payment service system conceived by the NPCI. Launched in 2012, RuPay was designed to be India’s domestic alternative to international card networks like Visa and MasterCard. By offering lower transaction costs for banks and merchants and operating within India, RuPay aimed to reduce dependence on foreign payment gateways and keep transaction data within the country. The government’s push for RuPay debit cards, particularly through schemes like Jan Dhan Yojana, significantly expanded its reach among the unbanked and underbanked populations.
The MDR Debate and Government’s Stance:
Over the past few years, discussions surrounding the Merchant Discount Rate (MDR) on UPI and RuPay transactions have been a recurring theme. MDR is a fee that a merchant pays to their bank for processing debit and credit card transactions. While credit card transactions have always incurred MDR, the debate intensified around debit cards and, more recently, UPI, as their usage surged. Banks and payment service providers argued that maintaining the infrastructure for these systems incurred significant costs, and a viable revenue model was necessary for sustainability.
However, the government consistently maintained its position that UPI and RuPay debit card transactions should remain free for consumers and small merchants to encourage widespread adoption. It recognized that imposing charges at the point of sale could deter users and hinder the "Digital India" objective. To offset the costs incurred by banks, the government, on several occasions, provided financial incentives and subsidies to banks for promoting RuPay debit cards and low-value BHIM-UPI transactions. This financial support underscored the government’s strategic intent to absorb the costs to ensure a frictionless digital payment experience for the masses.
Formalizing the Policy:
The recent gazette notification effectively formalizes this long-standing policy stance, giving it legal backing under the Payment and Settlement Systems Act, 2007. The Monday announcement clarifies that this zero-charge mandate is now explicitly enshrined in law for UPI transactions up to Rs 2,000 and all RuPay debit card payments, eliminating any ambiguity and providing a clear framework for all stakeholders. This move demonstrates the government’s resolve to institutionalize a policy that has proven instrumental in driving India’s digital payment revolution.
Supporting Data: The Unprecedented Growth of India’s Digital Payments
The government’s unwavering support for zero-charge policies on UPI and RuPay is underpinned by the phenomenal growth and widespread adoption of these payment methods. India has emerged as a global leader in digital payments, largely driven by the success of UPI.
UPI’s Meteoric Rise:
Since its inception, UPI has witnessed an astounding trajectory of growth. Monthly transaction volumes have soared from a mere few million in its early days to several billions. In recent times, UPI has consistently recorded over 10 billion transactions monthly, with values often exceeding Rs 15-18 trillion (approximately $180-220 billion). This makes UPI one of the fastest-growing and most adopted real-time payment systems in the world, far surpassing many developed economies in transaction volume.
This growth is not merely in numbers but also in penetration. UPI has reached virtually every segment of Indian society, from metropolitan cities to remote villages. It has become the preferred mode of payment for everything from street vendors and small kirana stores to large retail chains and online e-commerce platforms. Its simplicity, interoperability, and instant settlement features have made it indispensable for daily financial interactions.
RuPay’s Expanding Footprint:
While UPI captures the lion’s share of digital transaction headlines, RuPay has quietly built a formidable presence. As an indigenous card network, it has played a critical role in promoting financial inclusion, especially through government schemes like the Pradhan Mantri Jan Dhan Yojana (PMJDY), which provided basic bank accounts and RuPay debit cards to millions of previously unbanked citizens.
The number of RuPay cards in circulation has grown exponentially, often exceeding 600-700 million. This ensures that even those without smartphones or access to UPI apps can still participate in the digital economy through point-of-sale (POS) terminals. The government’s preference for RuPay in various subsidy disbursements and direct benefit transfers has further cemented its importance.
Economic Impact and Financial Inclusion:
The widespread adoption of UPI and RuPay has had a transformative impact on the Indian economy.
- Reduced Cash Dependency: It has significantly reduced the economy’s reliance on physical cash, leading to lower costs associated with printing, distributing, and managing currency.
- Formalization of the Economy: Digital transactions leave an electronic trail, aiding in tax compliance and bringing more economic activity into the formal sector. This is particularly beneficial for small businesses that previously operated primarily in cash.
- Increased Efficiency: Instant payments streamline business operations, improve cash flow for merchants, and reduce payment delays.
- Boost to MSMEs: Micro, Small, and Medium Enterprises (MSMEs) have been major beneficiaries, as they can accept digital payments without incurring prohibitive costs, expanding their customer base and operational efficiency.
- Global Recognition: India’s UPI model has garnered international acclaim, with several countries exploring similar payment architectures or partnering with India to integrate UPI for cross-border transactions, highlighting its innovative and robust design.
The government’s decision to keep small-value UPI and all RuPay debit card transactions free is a direct acknowledgment of these profound benefits and a strategic investment in the continued growth and stability of this digital infrastructure.
Official Responses: Reaffirming Commitment and Dispelling Misinformation
The Central government has been proactive in communicating its policy objectives and addressing any concerns or misrepresentations surrounding digital payment charges. The Ministry of Finance has consistently articulated the rationale behind its decisions, emphasizing sustainability and public benefit.
Ministry of Finance’s Stance on Digital Infrastructure:
The Ministry of Finance has repeatedly underscored that the overarching goal of these policies is to make India’s digital payment infrastructure "sustainable, competitive, and capable of supporting the country’s expanding digital economy." This statement is not merely a slogan but reflects a deeply considered strategy. For a digital payment system to thrive, it must be robust, secure, and accessible. By ensuring zero charges for small-value transactions, the government aims to keep the entry barrier low, encouraging mass adoption, which in turn fuels the network effect crucial for a payment system’s success.
The Ministry acknowledges that operating and maintaining such a vast digital infrastructure, including cybersecurity measures, fraud prevention mechanisms, and continuous technological upgrades, requires significant investment. However, its strategy has been to manage these costs through a combination of government support and, potentially, through alternative revenue models for higher-value transactions, rather than burdening the everyday user or small merchant with direct transaction fees on low-value payments.
Debunking "Unfounded Claims":
Crucially, the Ministry of Finance also took a firm stance against what it described as "unfounded, completely false and misleading" claims regarding external influences behind proposed policy changes. This was in response to earlier reports or rumors suggesting that external entities or lobbies were dictating the terms of India’s digital payment policies, particularly concerning the introduction of charges.
The government’s swift and categorical denial served to reaffirm its sovereignty over its economic and financial policies. It emphasized that decisions related to India’s payment ecosystem are made internally, based on national priorities and strategic objectives, with the welfare of its citizens and the growth of its indigenous digital infrastructure at the forefront. This strong rebuttal aimed to ensure public trust and confidence in the government’s commitment to its ‘Digital India’ vision.
NPCI’s Role and Alignment:
While the government sets the policy, the National Payments Corporation of India (NPCI) is the operational backbone of UPI and RuPay. NPCI, as a not-for-profit organization, works in close coordination with the government and the Reserve Bank of India. Its role involves not only developing and maintaining the payment infrastructure but also aligning its operational strategies with the government’s directives, including the zero-charge mandate. The synergy between government policy and NPCI’s execution has been pivotal in the success of India’s digital payment revolution.
Implications: A Balanced Approach to Digital Payment Evolution
The government’s decision to maintain zero charges on small UPI transactions and RuPay debit card payments carries significant implications for various stakeholders, shaping the future trajectory of India’s digital economy. It represents a nuanced approach, balancing widespread adoption with the long-term sustainability of the payment infrastructure.
For Consumers:
The immediate and most tangible benefit is for the common consumer. The assurance of no charges on UPI transactions up to Rs 2,000 means continued convenience and cost-free access to digital payments for daily needs. This fosters greater trust in digital transactions and encourages even wider adoption, especially among segments of the population still hesitant about using digital money due to perceived costs. It makes digital payments a default, friction-free option for small-value exchanges.
For Small Businesses and Merchants:
Small merchants, particularly those in the informal sector or operating with thin margins, are significant beneficiaries. The absence of transaction charges on small-value UPI payments and all RuPay debit card transactions means they can accept digital payments without incurring additional costs, which often proved prohibitive for them. This not only expands their customer base (as more people prefer digital payments) but also contributes to the formalization of their businesses, potentially opening doors to credit and other financial services. It levels the playing field, allowing even the smallest vendor to participate in the digital economy.
For Banks and Payment System Providers:
This is where the implications become more complex.
- Revenue Impact: For banks and payment system providers, the zero-charge mandate on these specific transaction types implies a direct loss of potential revenue from MDR. While the transaction values are small, their sheer volume could have generated substantial aggregate income.
- Cost Burden: Despite the zero-charge policy for end-users, banks and system providers continue to incur significant operational costs. These include maintaining the UPI and RuPay infrastructure, investing in cybersecurity, combating fraud, customer service, and technological upgrades. The absence of direct transaction fees for these segments means these costs must be borne either by other revenue streams, government subsidies, or through efficiency gains.
- Innovation Imperative: This situation pushes banks and payment providers to innovate and find alternative, sustainable revenue models. This could involve offering value-added services, premium features for higher-value transactions, or cross-selling other financial products. It fosters a competitive environment where providers must offer superior service and additional benefits to attract and retain customers.
- Government Support: It is important to note that the government has previously provided financial incentives to banks to promote RuPay debit cards and low-value BHIM-UPI transactions, acknowledging the costs involved. This may continue in some form to ensure the viability of the ecosystem.
The Future of MDR for Higher-Value UPI Transactions:
While the current notification guarantees zero charges for UPI transactions up to Rs 2,000, it also subtly creates room for a future merchant-fee framework for higher-value transactions. The government has previously clarified that any future Merchant Discount Rate (MDR) on UPI would be:
- Limited to certain high-value merchant transactions: This suggests a threshold above Rs 2,000, ensuring that everyday small payments remain free.
- Significantly lower than debit and credit card MDRs: This is crucial to maintain UPI’s cost-effectiveness compared to traditional card payments.
- Not an immediate introduction: The government clarified that this is part of a proposed amendment to the Payment and Settlement Systems Act, 2007, and does not mean UPI charges are being introduced immediately. It requires further legislative action.
If MDR is eventually introduced for higher-value transactions, the UPI and Services Steering Committee, headed by NPCI, would be tasked with deciding the applicable rate, but only after Parliament passes the necessary Bill. This layered approach aims to:
- Create a Sustainable Revenue Model: As transaction volumes continue to rise, so does the need for investment in infrastructure, cybersecurity, and fraud prevention. A carefully calibrated MDR on higher-value transactions could provide the necessary revenue stream to sustain and further develop the UPI ecosystem without burdening the masses.
- Balance Growth and Viability: It allows the system to remain free for the majority of users (small transactions) while ensuring that the infrastructure supporting all transactions remains robust and innovative through contributions from higher-value commercial activities.
- Maintain Competitiveness: By keeping MDR significantly lower than existing card networks, UPI would retain its competitive edge, encouraging merchants to continue preferring it for larger transactions as well.
Impact on Digital Economy and Global Leadership:
This policy reinforces India’s position as a global leader in accessible digital payments. By prioritizing user convenience and affordability, India is setting a precedent for how a large, diverse economy can successfully transition towards digital transactions. The tiered approach to transaction charges, with zero charges for small values and a potential future MDR for higher values, demonstrates a mature understanding of payment system economics. It aims to foster a dynamic ecosystem where innovation thrives, costs are managed, and financial inclusion remains at the core.
The continued commitment to a zero-charge regime for small-value UPI and RuPay debit card payments is a strategic investment in the future of India’s digital economy, ensuring that the benefits of financial technology reach every citizen and business, driving growth and inclusion for years to come.
