
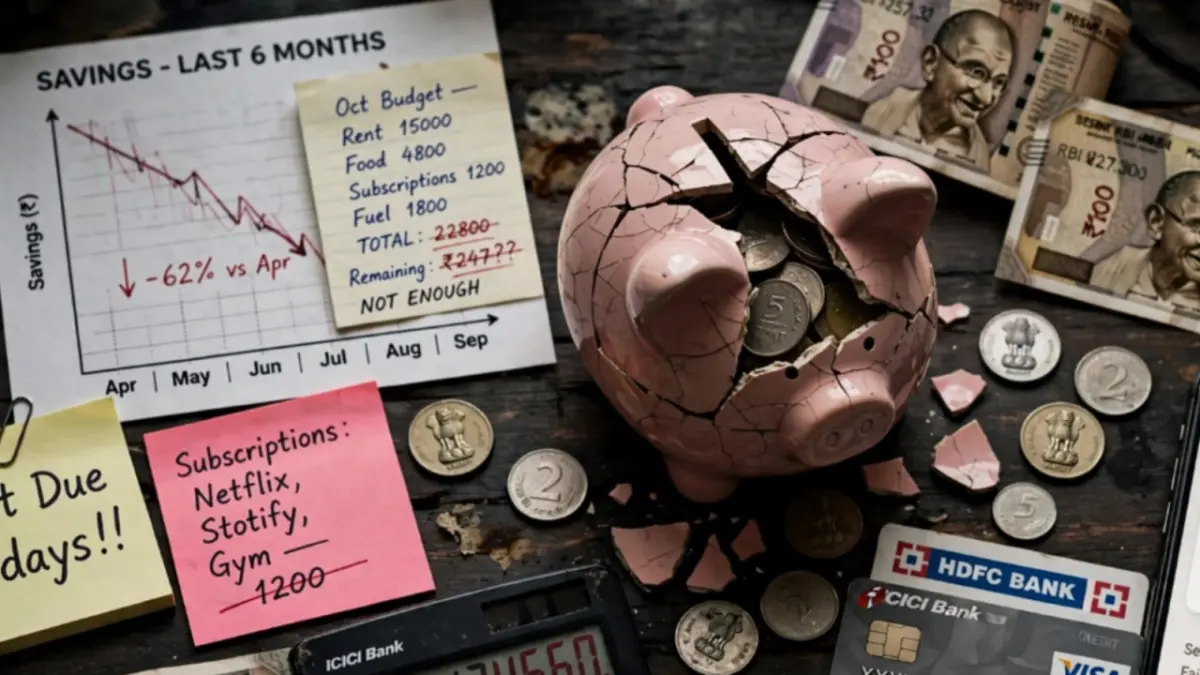
Mumbai, India – October 26, 2026 – As India’s demographic dividend continues to shape its economic future, a new generation of earners is taking center stage. Gen Z, individuals born between the mid-1990s and early 2010s, now constitutes a significant and growing portion of the nation’s workforce. According to the Great Place To Work India’s Great Mid-size Workplaces 2026 report, this dynamic cohort is projected to make up 26% of the Indian workforce by 2026. Their entry into the professional world coincides with an unprecedented era of digital transformation, offering unparalleled access to financial products, seamless digital payments, and a diverse array of investment opportunities. Yet, this newfound financial agency, paradoxically, has not uniformly translated into robust financial security.
The paradox lies in the confluence of higher earning potential and pervasive financial vulnerabilities. While Gen Z enjoys the convenience of instant transactions and a wealth of investment options at their fingertips, many find themselves grappling with lifestyle inflation, burgeoning credit card debt, and a foundational lack of comprehensive financial planning. This complex interplay of opportunity and challenge necessitates a deeper dive into their financial behaviors and the expert guidance crucial for their long-term economic well-being.
The Evolving Financial Landscape for Gen Z in India: A Chronology of Influence
The financial journey of Gen Z is inherently distinct from that of previous generations, largely shaped by the digital age in which they were raised. Unlike their predecessors, who might have learned about finance through traditional banking or family advice, Gen Z grew up with smartphones as extensions of themselves, witnessing the rapid ascent of e-commerce, social media, and fintech innovations. This environment has profoundly influenced their perceptions and habits concerning money.
Their formative years coincided with the widespread adoption of digital payments in India, a movement accelerated by initiatives like demonetization and the proliferation of the Unified Payments Interface (UPI). This constant exposure to frictionless transactions has normalized immediate gratification and made the act of spending less tangible. Credit, too, has become more accessible, not just through traditional credit cards but also via nascent "Buy Now, Pay Later" (BNPL) schemes and personal loan apps, often promoted through social media channels where Gen Z spends a significant portion of their time.
Furthermore, the information age, while democratizing access to financial knowledge, has also brought with it a deluge of unfiltered, often misleading, advice. The rise of social media influencers, online trading forums, and the gamification of investing platforms have cultivated an environment where quick gains are often prioritized over sound, long-term strategies. This chronological evolution of their financial ecosystem has created a generation that is financially active but often lacks the foundational discipline and critical discernment necessary to navigate its complexities effectively. Their entry into the workforce, therefore, brings with it a pre-existing set of financial habits and predispositions that experts are now striving to reorient towards sustainable prosperity.
Dissecting the Data: Supporting Trends and Behaviors
The latest data paints a nuanced picture of Gen Z’s financial realities, highlighting both their economic contributions and the significant hurdles they face.
Workforce Demographics and Initial Earnings
The statistic that Gen Z will constitute 26% of the Indian workforce by 2026 underscores their growing economic power and potential. As they enter the professional arena, many command competitive starting salaries, particularly in fast-growing sectors like technology and services. However, this higher income, as Ramesh Vishwanathan, CEO, FPSB India, points out, does not automatically equate to financial security. "Young earners today have access to financial information, credit, and investment options, but access does not automatically translate into financial preparedness. A common mistake is assuming that higher income means security," Vishwanathan explains, highlighting a critical misconception.
Spending Habits: The Grip of Lifestyle Inflation
One of the most significant challenges facing young earners is the phenomenon of lifestyle inflation. As salaries grow, so too do discretionary expenses, often leaving little room for crucial savings and future investments. Vishwanathan notes, "As young earners’ salaries grow, lifestyle expenses can rise, leaving less room for savings and future goals." This observation is strongly supported by recent surveys and transactional data.

The Deloitte’s 2026 India Gen Z and Millennial Survey revealed that a striking 20% of Indian Gen Z respondents struggle to meet their monthly living expenses. More alarmingly, 54% reported delaying major life decisions—such as marriage, having children, or buying a home—due to their financial situation. The survey also found that over 60% of Gen Z and millennials felt that housing affordability directly impacted their career decisions, forcing them to prioritize higher-paying jobs over passion or work-life balance in certain locations.
Further insights into Gen Z’s spending patterns come from SalarySe, which analyzed over 5.2 lakh salaried Gen Z users and millions of UPI transactions. This data provides a granular view of where their money goes:

- Bills and Subscriptions: A significant 20% of spending is allocated to recurring bills and various digital subscriptions (streaming services, apps, online gaming, fitness). This reflects a modern consumption pattern where access to digital content and services is prioritized.
- Groceries: 15.7% is spent on groceries, indicating a basic cost of living.
- Shopping: 11.9% is dedicated to shopping, encompassing everything from fashion and electronics to online retail therapy.
- Travel: Around 5% is spent on travel, suggesting a desire for experiences and exploration, often influenced by social media trends.
- Discretionary Spending: A substantial 32% of spending across both 18-23 and 24-29 age groups falls under discretionary categories. This broad category includes dining out, entertainment, impulse purchases, and lifestyle upgrades driven by peer and social media influence.
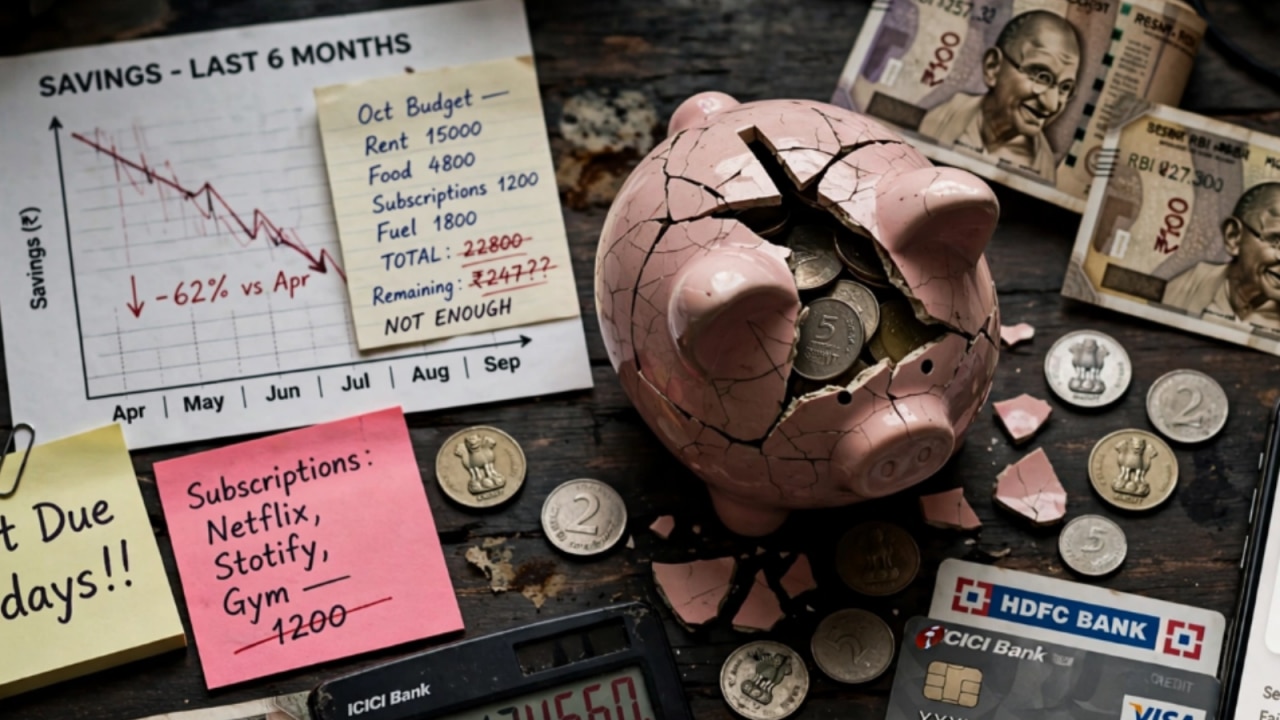
This data underscores the prevalence of lifestyle inflation, where an increase in income is often immediately absorbed by a corresponding increase in non-essential spending. This trend, combined with persistent inflation, creates a precarious financial situation for many young Indians.
The Rise of Digital Credit and Mounting Debt
The ease of digital transactions extends beyond spending to credit access, which is growing at an alarming rate among Gen Z. TransUnion CIBIL data, reported by Financial Express, indicates that Gen Z accounted for 50% of new credit card holders in India in March 2026, a significant jump from 43% just a year prior. While credit cards offer convenience and rewards, their misuse can lead to substantial debt.

The report further highlighted troubling trends: nearly 28% of Gen Z first-time cardholders accumulated balances exceeding Rs 25,000 within three months of receiving their card. Furthermore, a staggering 69% took on another credit product within a year, suggesting a pattern of increasing reliance on credit. The source of this credit is also evolving, with TransUnion CIBIL-FIDC data showing that around 46% of credit originations to Gen Z borrowers in the first half of 2026 came from Non-Banking Financial Companies (NBFCs), which often cater to higher-risk borrowers and may carry higher interest rates.
Deepak Keshri, Certified Financial Planner and an expert with Capital Trust, paints a grim picture of this debt-fueled lifestyle. He observes that many young earners "are trapped in a debt-fueled lifestyle, spending heavy chunks of their salaries on EMIs for depreciating assets like gadgets, luxury cars, and dining out under peer and social media pressure." This spending, he notes, often leaves them with "zero emergency funds and depend entirely on basic corporate health insurance." The psychological toll is undeniable: "When their salary disappears into credit card bills and EMIs on day one, mental stress inevitably follows," Keshri adds.

Investment Trends: Chasing Quick Returns and Speculation
Beyond spending and debt, Gen Z’s investment behaviors also raise concerns. Parul Maheshwari, a Certified Financial Planner, points out a tendency for impatience and ad-hoc decision-making. "I have found Gen Z to lack patience, make ad hoc investment decisions and chase the best-performing asset class in the recent past for higher returns," she states. This often manifests in a pursuit of speculative investments like cryptocurrency, options trading, or rapidly fluctuating stocks, driven by the desire for quick wealth rather than a methodical, long-term approach.
Keshri corroborates this, stating that "barely 20% – 30% of young earners truly grasp goal-based investing—and even among them, many fall for short-term speculative trends like crypto, options, etc." This speculative mindset, coupled with limited financial literacy, often exposes them to higher risks, potentially eroding their capital rather than building it steadily. The allure of "get rich quick" schemes, amplified by social media success stories, can overshadow the fundamental principles of diversification, risk management, and patient compounding.

Official Responses: Expert Guidance for Financial Resilience
In light of these pressing challenges, financial experts are offering critical advice tailored to help Gen Z navigate their complex financial landscape and build a secure future. Their recommendations consistently emphasize preparedness, responsible behavior, and a shift in mindset.
The Expert Consensus: Foundations of Financial Health
Ramesh Vishwanathan stresses that financial planning transcends mere wealth accumulation; it is about establishing clarity and building resilience. He advises Gen Z to:

- Understand Cash Flows: The starting point for any sound financial plan is a clear understanding of one’s income and expenses. This involves tracking where money comes from and where it goes, identifying spending patterns, and distinguishing between essential and discretionary outlays. This granular insight allows individuals to pinpoint areas for savings and optimize their financial flow.
- Identify Priorities and Set Clear Goals: Before making financial decisions, young earners must define what truly matters to them. Whether it’s buying a home, funding higher education, starting a business, or securing retirement, clear, measurable financial goals provide direction and motivation for saving and investing.
- Build Financial Resilience: This involves creating a robust safety net. Vishwanathan particularly highlights the importance of an emergency reserve (typically 3-6 months of living expenses), adequate protection (health and life insurance), and responsible debt management. The goal is to weather unexpected financial shocks without derailing long-term plans.
- Start Retirement Planning Early: The power of compounding makes early retirement planning incredibly impactful. Vishwanathan emphasizes the need to begin saving and investing for retirement as soon as possible, accounting for inflation and the changing financial responsibilities that come with age. Even small, consistent contributions made early can accumulate into substantial wealth over decades.
- Align Investments with Goals: Investments should not be random or driven by market fads. Instead, they must be strategically aligned with specific financial priorities and risk tolerance. This means choosing appropriate asset classes and investment vehicles that support short-term, medium-term, and long-term goals.
Vishwanathan concludes that "Financial planning is an ongoing process of making informed decisions, preparing for uncertainty, and building financial confidence over time." It is a dynamic journey that requires continuous evaluation and adjustment.
Key Strategies for Practical Implementation
Parul Maheshwari offers actionable strategies for shifting Gen Z’s financial habits from reactive spending to proactive saving:

- Reverse the Spending-Before-Saving Approach: Maheshwari urges a fundamental shift in mindset. Instead of spending first and saving what’s left (which is often nothing), she advocates for the "pay yourself first" principle. She suggests saving at least 25-30% of monthly earnings immediately upon receiving income, and only then allocating the remainder for expenses. This ensures consistent savings regardless of discretionary spending.
- Increase SIP Investments Alongside Income: As income grows, so should systematic investment plan (SIP) contributions. This allows individuals to leverage their increased earning capacity to accelerate wealth creation through disciplined, regular investments in mutual funds or other instruments. This strategy automates wealth building and hedges against lifestyle inflation.
- Treat Credit Cards as a Payment Tool, Not Extra Income: Maheshwari strongly cautions against viewing credit cards as an extension of one’s income. They are designed for convenience and building a credit history, not for funding a lifestyle beyond one’s means. "Pay the full outstanding amount every month and avoid revolving credit-card debt. This is a must for Gen Z," she asserts. Carrying a balance incurs high interest rates, creating a debt spiral that can be incredibly difficult to escape. This disciplined approach is crucial for maintaining a healthy credit score and financial solvency.
Deepak Keshri’s call for "professional, holistic financial coaching" underscores the complexity and emotional aspects of money management. He believes that personalized guidance can help young earners overcome behavioral biases, develop goal-based strategies, and build the financial discipline they currently lack. Such coaching can provide the structure and accountability needed to break free from debt cycles and build a secure future.
Implications: Societal, Economic, and the Path Forward
The financial behaviors and challenges faced by Gen Z have far-reaching implications, extending beyond individual households to impact the broader economy and society.

Societal and Economic Ramifications
- Delayed Milestones and Reduced Quality of Life: The Deloitte survey’s finding that 54% of Gen Z delayed major life decisions due to financial constraints is a significant societal concern. Delayed homeownership, family formation, and entrepreneurial ventures can have ripple effects, impacting consumer spending, housing markets, and overall economic dynamism. A generation burdened by debt and financial stress may experience lower life satisfaction and increased mental health issues, as suggested by Keshri.
- Stagnant Wealth Accumulation: A lack of emergency funds and heavy reliance on credit means that many Gen Z individuals are perpetually on a financial tightrope. Without the ability to save and invest consistently, their capacity for long-term wealth accumulation is severely hampered. This could lead to a future where a significant portion of the workforce reaches retirement age with insufficient savings, placing potential strain on social welfare systems.
- Impact on Economic Growth: If a large segment of the population is struggling with debt and unable to invest in productive assets, it can dampen overall economic growth. Consumer spending might be directed more towards debt servicing than towards goods and services that stimulate the economy. Furthermore, reduced capital formation by individuals can affect the availability of domestic capital for investment in industries and infrastructure.
- Shifting Consumer Landscape: Gen Z’s spending patterns, with a high allocation to digital subscriptions and discretionary items, are reshaping consumer markets. Businesses must adapt to these preferences, but they also highlight a potential disconnect between immediate gratification and long-term financial stability.
The Path Forward: Cultivating Financial Wellness
Addressing Gen Z’s financial challenges requires a multi-pronged approach involving individuals, educators, financial institutions, and policymakers:
- Enhanced Financial Literacy Education: Integrating practical financial education into school curricula and making it accessible through digital platforms is crucial. This should go beyond basic budgeting to cover topics like debt management, investing fundamentals, risk assessment, and the psychological aspects of money.
- Responsible Product Design: Financial institutions have a responsibility to design products that are transparent, easy to understand, and promote responsible financial behavior. This includes clearer communication around credit card interest rates, BNPL terms, and investment risks. Incentivizing saving and responsible credit use could also be beneficial.
- Accessibility to Professional Advice: Making certified financial planning more accessible and affordable for young earners is vital. Simplified, digital-first advisory services could bridge the gap between complex financial concepts and Gen Z’s preferred mode of interaction.
- Promoting a Culture of Savings: Societal norms and media narratives can play a role in promoting a culture of saving and delayed gratification, counteracting the pervasive influence of consumerism and instant gratification.
- Policy Support: Government policies could explore incentives for young savers, review regulations around predatory lending, and support initiatives that enhance financial literacy.
In conclusion, Gen Z stands at a pivotal juncture, armed with unprecedented access to financial tools but often lacking the wisdom and discipline to wield them effectively. While their entry into the workforce injects dynamism into the economy, their current financial trajectory, marked by lifestyle inflation, debt, and speculative investments, poses significant risks. The collective wisdom of financial experts offers a clear roadmap: prioritize preparedness, embrace responsible debt management, cultivate a disciplined savings habit, and embark on long-term goal-based investing. By heeding this advice, India’s Gen Z can transform their inherent potential into tangible financial security, ensuring not only their individual prosperity but also contributing to the nation’s sustained economic growth.

Find your daily dose of All Latest News including Sports News, Entertainment News, Lifestyle News, explainers & more. Stay updated, Stay informed- Follow DNA on WhatsApp.
