

The Indian automotive sector, a primary barometer for the nation’s economic health, showcased a robust performance in September 2026. As the industry prepared for the peak of the festive season, the top 10 best-selling passenger vehicles collectively reached a milestone of 1,91,332 units. This performance represents a significant 15.45% year-on-year (YoY) growth compared to the 1,65,725 units sold by the same elite group in September 2025. This volume increase of 25,607 units underscores a resilient consumer appetite and a strategic alignment of product portfolios by the country’s leading manufacturers.
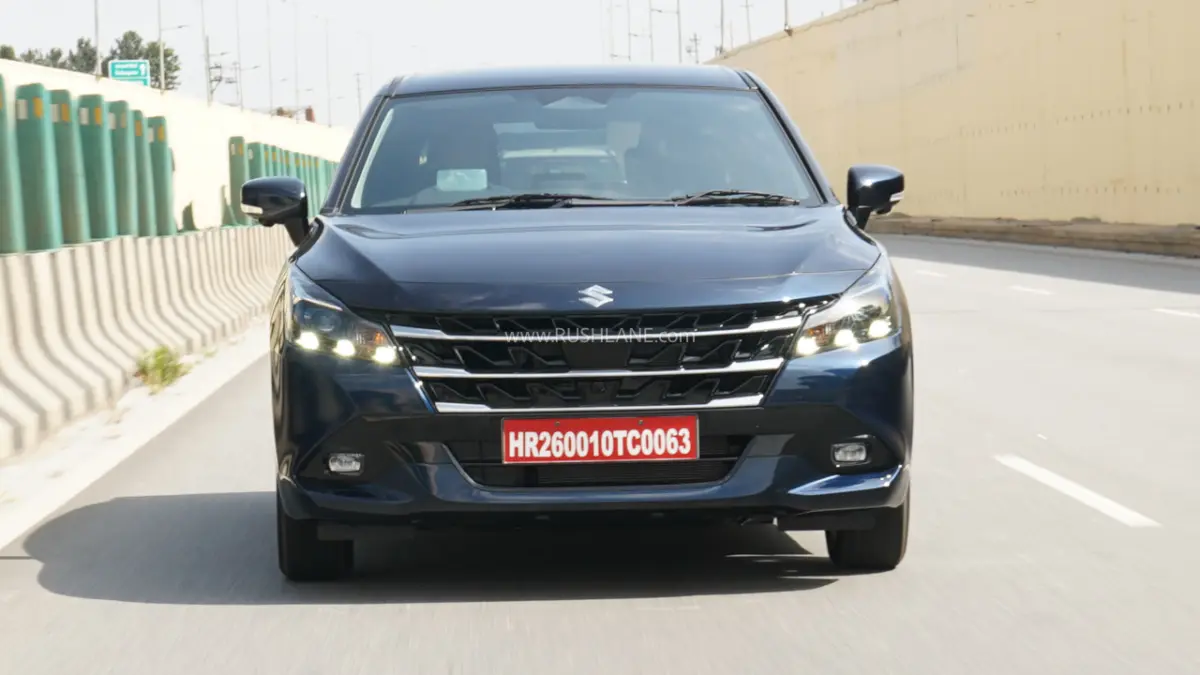
At the heart of this growth was Maruti Suzuki, which fortified its market leadership by securing six positions within the top 10. However, the standout story of the month was the meteoric rise of the Maruti Suzuki Baleno. Following a highly anticipated facelift, the premium hatchback not only reclaimed its position as India’s top-selling car but did so with a staggering 92.76% YoY growth.
Main Facts: The September Sales Snapshot
The sales data for September 2026 reveals a market in transition, where established leaders are being challenged by internal shifts and external competition. The top 10 list is dominated by Maruti Suzuki (6 models), followed by Tata Motors (2 models), Hyundai (1 model), and Mahindra (1 model).
The Leaderboard Highlights:
- Maruti Baleno: 25,392 units (+92.76% YoY)
- Tata Nexon (incl. EV): 20,456 units (-9.38% YoY)
- Tata Punch (incl. EV): 20,333 units (+27.95% YoY)
- Maruti Fronx: 19,282 units (+40.06% YoY)
- Maruti WagonR: 18,835 units (+22.40% YoY)
- Maruti Dzire: 17,754 units (-11.40% YoY)
- Hyundai Creta (incl. EV): 17,657 units (-6.38% YoY)
- Maruti Swift: 17,399 units (+11.91% YoY)
- Mahindra Scorpio (N & Classic): 17,313 units (-5.76% YoY)
- Maruti Ertiga: 16,911 units (+39.59% YoY)
The combined volume of 1,91,332 units also reflected a healthy month-on-month (MoM) increase of 4.53%, adding 8,295 units over August 2026’s tally of 1,83,037 units. This sequential growth is particularly telling, as it suggests that the inventory push for the October festive period began in earnest during the final weeks of September.
Chronology: The Road to September’s Surge
To understand the September 2026 figures, one must look at the preceding months and the strategic launches that shaped the quarter.
The Pre-Festive Build-up (July–August 2026):
The Indian market witnessed a slight cooling in early Q3 2026 as consumers delayed purchases in anticipation of new launches and festive discounts. Manufacturers utilized this period to clear older inventory and ramp up production for updated models. In August 2026, the top 10 cars sold 1,83,037 units, with the Maruti Baleno starting to show signs of a recovery following its mid-year update.
The Facelift Catalyst (Late August 2026):
The launch of the 2026 Maruti Baleno facelift was the primary catalyst for the September numbers. By refreshing the aesthetics and enhancing the tech suite of the premium hatchback, Maruti Suzuki addressed the "fatigue" that had begun to affect the model’s sales in late 2025. This move effectively countered the rising popularity of compact SUVs in the same price bracket.
The September Execution:
As September commenced, the "Shradh" period (traditionally a slow buying period in some parts of India) was offset by aggressive dispatch strategies to dealerships. By the third week of September, the demand for the new Baleno and the steady popularity of Tata’s SUV duo (Nexon and Punch) propelled the numbers to their final 1.91 lakh unit total.

Supporting Data: A Deep Dive into the Performance
The Baleno Phenomenon
The Maruti Baleno’s performance was nothing short of extraordinary. With 25,392 units sold, it nearly doubled its September 2025 performance of 13,173 units. The 12,219-unit volume gain accounted for nearly half of the total growth seen across the entire top 10 list. On a month-on-month basis, the Baleno grew by 61.26%, gaining 9,646 units over August. This surge was so significant that it single-handedly compensated for the sales declines recorded by five other models in the top 10.
The SUV Tussle: Tata vs. The Rest
Tata Motors continued to demonstrate its dominance in the SUV space, though with mixed results. The Nexon, while securing the second spot with 20,456 units, saw a 9.38% YoY decline. This is likely due to increased competition from the Maruti Fronx and the Mahindra XUV 3XO. Conversely, the Tata Punch grew by nearly 28% YoY, reaching 20,333 units. The gap between the Nexon and Punch has narrowed to just 123 units, suggesting an internal shift in preference toward the more compact, value-driven Punch.
The Mid-Table Dynamics
The Maruti Fronx emerged as a consistent winner, being the only model alongside the Baleno to register growth in both YoY (+40.06%) and MoM (+2.95%) metrics. Its crossover appeal continues to bridge the gap between hatchbacks and SUVs. Meanwhile, the Hyundai Creta and Mahindra Scorpio faced slight YoY headwinds, declining by 6.38% and 5.76% respectively. However, both showed MoM recoveries (Creta +8.40%, Scorpio +11.15%), indicating that demand for mid-size and rugged SUVs remains fundamentally strong, even if hampered by temporary supply chain adjustments.
The Decline of the Sedan?
The Maruti Dzire, once a perennial top-three contender, recorded the sharpest YoY decline in the list at 11.40%. With 17,754 units sold, it fell to sixth place. This trend highlights the continuing migration of Indian buyers away from three-box sedans toward crossovers and SUVs. Even with its strong fleet-market presence, the Dzire is feeling the pressure from its own stablemate, the Ertiga, which saw a nearly 40% YoY jump as buyers prioritize cabin space and utility.
Official Responses and Industry Sentiment
While official statements from individual manufacturers are often guarded, industry analysts and spokespeople from the Society of Indian Automobile Manufacturers (SIAM) have pointed to several key drivers for the September performance.
Analyst View on Maruti’s Strategy:
"Maruti Suzuki’s ability to place six models in the top 10 is a testament to their unparalleled distribution network and the successful ‘premiumization’ of their entry-level models," says Anirudh Sen, a senior automotive consultant. "The Baleno facelift was a tactical masterstroke. By doubling down on the premium hatchback segment when others are exiting it, they have captured a massive share of the urban millennial market."
Tata Motors’ Focus on Powertrain Diversity:
A spokesperson for Tata Motors noted during a recent investor call that their strategy of offering "multi-powertrain options" (Petrol, Diesel, CNG, and EV) for the Nexon and Punch has been vital. "While the YoY numbers for Nexon show a dip, the EV penetration within that model continues to grow, ensuring higher margins and future-proofing our market share," the official stated.
The Inventory Factor:
Dealership associations (FADA) have noted that the high dispatch numbers in September were also a result of manufacturers filling the "pipeline" for the 42-day festive period. "We are seeing high stock levels at dealerships, but the inquiry rate for the Baleno and Fronx is exceptionally high, which gives us confidence that these dispatches will convert to retail sales quickly," a FADA representative mentioned.

Implications: What This Means for the Future
The September 2026 sales figures provide a clear roadmap for the final quarter of the year and into 2027.
1. The Resurgence of the Premium Hatchback:
For the past three years, the narrative has been dominated by the "SUV-ification" of the Indian market. However, the Baleno’s success suggests that there is still a massive market for premium hatchbacks if they offer the right mix of technology, fuel efficiency (likely through advanced hybrid or CNG options), and modern design.
2. The EV Integration:
The fact that Nexon, Punch, and Creta figures now include their electric versions as standard practice highlights that EVs are no longer a "niche" category but a core component of mainstream sales. As charging infrastructure expands, expect EVs to contribute a larger percentage of the volume within these top 10 nameplates.
3. Consolidation at the Top:
The "Big Three"—Maruti, Tata, and Hyundai—along with a surging Mahindra, are effectively locking out the top 10. For smaller players, the barrier to entry into the high-volume segment is becoming increasingly difficult to breach, forcing them to focus on niche lifestyle segments or premium luxury tiers.
4. The 2027 Outlook:
As we approach 2027, the industry is bracing for tighter emission norms and safety mandates. The growth seen in September 2026 suggests that consumers are willing to pay the premium for updated, safer, and more tech-heavy vehicles. The focus for manufacturers will now shift from mere volume to "value per unit," as seen in the success of the Fronx and Ertiga.
In conclusion, September 2026 has set a high benchmark for the Indian auto industry. While the Maruti Baleno is the undisputed champion of the month, the overall growth of the top 10 indicates a healthy, evolving market. As the festive season reaches its zenith, the industry will be watching closely to see if this momentum can be sustained or if the high inventory levels will lead to a cooling period in the new year. For now, the Indian car buyer remains the king, with more choices and better technology than ever before.
