
The Indian commercial vehicle (CV) industry, often regarded as the primary barometer of the nation’s economic health, has signaled a robust recovery and expansion phase. In a landmark performance for the month of September 2026, retail sales across the country crossed the prestigious 1.03 lakh unit mark. This surge reflects a burgeoning demand for logistics, infrastructure development, and last-mile connectivity, underscoring a period of intensive industrial activity.
According to the latest retail data, the segment saw a collective sale of 1,03,557 units. This figure represents a staggering year-on-year (YoY) growth of 37.62% compared to the 75,246 units sold in September 2025. This volume gain of over 28,000 units within a single year suggests that the headwinds previously facing the transport sector—ranging from high interest rates to fluctuating fuel prices—are being countered by aggressive government infrastructure spending and a revitalized manufacturing landscape.
The Core Narrative: A Month of Unprecedented Growth
The momentum in September was not merely a reflection of yearly comparisons but also showcased a strong sequential recovery. Month-on-month (MoM) sales improved by 14.09% over August 2026’s 90,769 units. This upward trajectory is particularly significant as it aligns with the end of the second quarter (Q2) of the fiscal year, a period where fleet operators typically ramp up procurement in anticipation of the festive season and increased agricultural output.
The market remains highly consolidated, with the "Big Three"—Tata Motors, Mahindra & Mahindra, and Ashok Leyland—commanding approximately 80% of the total retail volume. However, the month was also characterized by a universal rise in performance, as all eight major listed manufacturers registered positive growth, indicating that the tide is rising for all players in the ecosystem.
Chronology of Performance: From Post-Monsoon Recovery to Festive Readiness
To understand the September surge, one must look at the preceding months of 2026. The early part of the year saw a steady but cautious growth pattern as the industry adjusted to new emission norms and evolving logistics policies. By August 2026, the market had reached a respectable 90,769 units. However, as the monsoon began to recede in many parts of the country by September, construction activities resumed at full scale, driving the demand for tippers and heavy-duty trucks.
Furthermore, the e-commerce sector began its annual "Big Sale" preparations in September, leading to a massive spike in demand for Light Commercial Vehicles (LCVs) and Small Commercial Vehicles (SCVs) for last-mile delivery. This chronological alignment of infrastructure restarts and festive logistics planning created a "perfect storm" of demand that pushed retail figures beyond the six-figure threshold.
Supporting Data: Manufacturer-Wise Breakdown
The Market Leaders: Tata, Mahindra, and Ashok Leyland
Tata Motors: Maintaining its status as the market bellwether, Tata Motors recorded 35,931 units in September 2026. This is a 46.96% jump from the 24,449 units sold in the same month last year. Tata’s contribution to the overall segment growth cannot be overstated; its volume gain of 11,482 units accounted for roughly 41% of the total industry-wide increase. The company’s market share for the month stood at a dominant 34.70%.

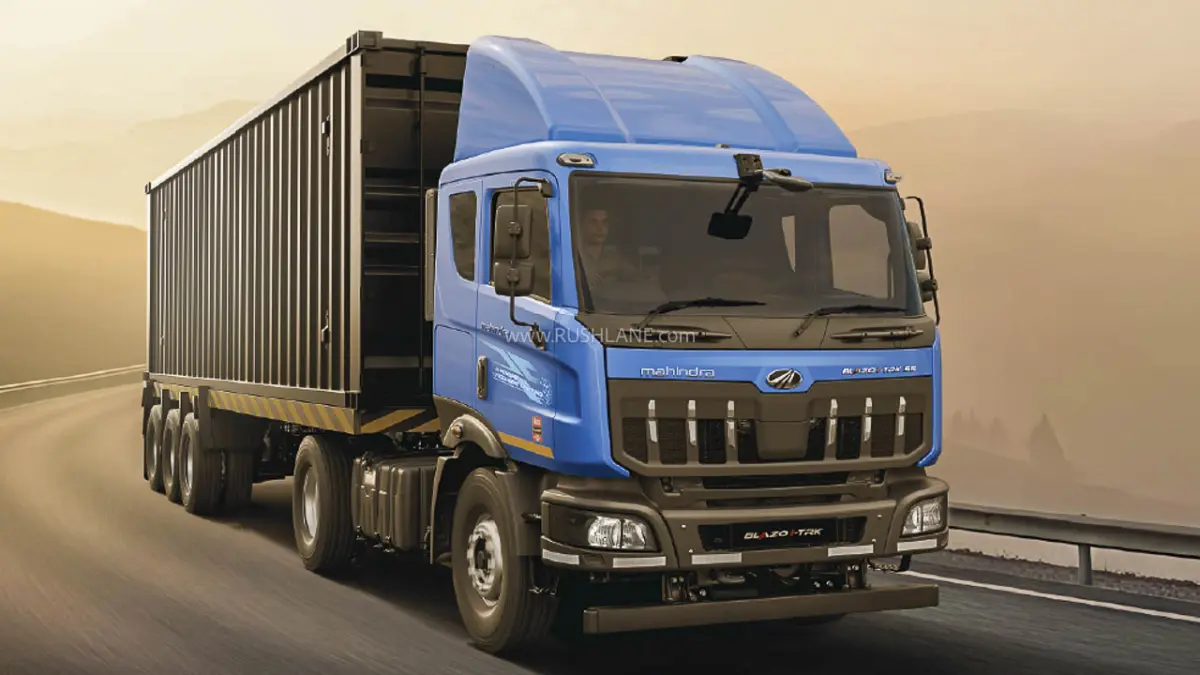
Mahindra & Mahindra: Occupying the second spot, Mahindra continues to leverage its strength in the pick-up and LCV segments. The company sold 27,677 units, a growth of 25.84% over the 21,994 units sold in September 2025. With a market share of 26.73%, Mahindra remains a critical player in rural and semi-urban logistics.
Ashok Leyland: The Chennai-based manufacturer posted a strong performance with 19,223 units, marking a 36.33% YoY increase. Its market share of 18.56% reflects its continued resilience in the Medium and Heavy Commercial Vehicle (M&HCV) space, particularly in the bus and haulage segments.
The Mid-Tier and Niche Players
VECV (Volvo Eicher Commercial Vehicles): VECV secured the fourth position with 8,309 units, growing 25.70% YoY. The brand has been successful in positioning itself as a technology leader, gaining an 8.02% market share.
Maruti Suzuki: Known for its "Super Carry" mini-truck, Maruti Suzuki registered 4,352 units, a 29.02% growth. While its market share is smaller at 4.20%, it remains a vital competitor in the entry-level SCV market.
Force Motors: Specializing in ambulances and school buses, Force Motors recorded 2,301 units, a 37.05% increase. Their niche focus has allowed them to maintain a steady 2.22% market share.
Daimler (BharatBenz): Daimler emerged as the "growth star" in terms of percentage, posting a 62.52% increase to 2,077 units. This suggests a growing preference among premium fleet operators for high-efficiency, long-haul trucks.
SML Isuzu: The manufacturer registered 1,286 units, a 39.18% increase, rounding off a month where every major player saw double-digit growth.

Fuel Dynamics: Diesel Dominance vs. The Electric Transition
The energy mix in the Indian CV sector provides a fascinating look into the industry’s transition. Diesel remains the undisputed king of the road, accounting for 80.76% of all retail sales in September 2026. This is a slight increase from August’s 78.77%, likely due to the surge in heavy-duty long-haul trucking which still relies heavily on the torque and range of diesel engines.
However, the year-on-year data tells a story of gradual decarbonization:
- Electric Vehicles (EVs): The most significant shift is seen in the EV space. Electric commercial vehicles now account for 4.04% of the market, nearly doubling their 2.16% share from September 2025. While this is a slight dip from the 5.18% share seen in August 2026 (likely due to a surge in diesel tipper sales for construction), the annual growth trend is undeniable.
- CNG/LPG: These alternative fuels held a 12.07% share, a slight increase from the previous year’s 11.45%.
- Petrol/Ethanol: This segment saw a decline, dropping to 3.11% from 4.14% a year ago, as buyers in the small vehicle segment migrate either toward CNG for lower running costs or EVs for future-proofing.
Official Responses and Industry Sentiment
While specific executive statements were not released alongside the raw data, industry analysts and dealer bodies like the Federation of Automobile Dealers Associations (FADA) have pointed toward several key drivers.
"The crossing of the 1-lakh mark in September is a psychological and economic milestone," says a senior automotive analyst. "It indicates that the replacement cycle for older fleets is in full swing, and the government’s PM Gati Shakti National Master Plan is finally translating into high-volume equipment orders at the ground level."
Dealers have reported that while inventory levels are manageable, there is a high demand for "ready-to-use" fully built vehicles rather than just chassis, as operators want to deploy assets immediately to capture festive demand. There is also a cautious optimism regarding the "Scrappage Policy," which is slowly beginning to incentivize owners of 15-year-old commercial vehicles to trade them in for modern, fuel-efficient models.
Implications for the Indian Economy
The robust performance of the CV sector in September 2026 has several far-reaching implications:
1. Infrastructure as a Growth Engine
The heavy growth in Tata and Ashok Leyland’s volumes suggests that the construction of highways, bridges, and dedicated freight corridors is accelerating. The demand for tippers and multi-axle vehicles is a direct lead indicator of steel and cement consumption, pointing toward a healthy secondary sector.

2. The E-commerce Logistics Boom
The 25-30% growth in the LCV segments (dominated by Mahindra and Maruti) highlights the deepening penetration of e-commerce into Tier-2 and Tier-3 cities. As "Quick Commerce" becomes the norm in urban centers, the demand for small, agile delivery vehicles is expected to remain on an upward trajectory.
3. Transition to Green Logistics
The doubling of the EV market share YoY is a testament to the success of FAME (Faster Adoption and Manufacturing of Hybrid and Electric Vehicles) incentives and the increasing availability of charging infrastructure. While diesel still dominates, the "tipping point" for electric LCVs in urban delivery appears to be approaching.
4. Supply Chain Resilience
The fact that all eight manufacturers grew simultaneously suggests that the global supply chain issues—specifically semiconductor shortages—that plagued the industry in previous years have been largely resolved. Indian manufacturers are now operating at high capacity, supporting the "Make in India" initiative.
Conclusion
September 2026 will be remembered as the month the Indian commercial vehicle industry proved its mettle. Surpassing 1.03 lakh units in retail sales is not just a win for manufacturers like Tata and Mahindra; it is a signal that the Indian economy is moving at a high velocity. As the industry heads into the final quarter of the calendar year, the focus will likely shift toward maintaining this momentum while navigating the complexities of the green energy transition. For now, the wheels of Indian commerce are turning faster than ever, driven by a blend of traditional diesel power and a rapidly growing electric future.
