The Indian automotive industry, long a cornerstone of the nation’s manufacturing sector, continues to solidify its position as a pivotal global hub for vehicle exports. According to the latest industry data for the first half of the 2027 fiscal year (H1 FY2027), spanning April to September 2026, car exports from India registered a modest but significant growth of 1.25% year-on-year.
Total export volumes reached 4,51,479 units, up from 4,45,884 units during the same period in the previous fiscal year. While the domestic market has seen an explosive surge in demand, the export sector’s performance reveals a complex narrative of shifting manufacturer dominance, the rising global appetite for Indian-made SUVs, and a strategic realignment of production priorities among major automakers.
Executive Summary: The State of Indian Car Exports
The 1.25% growth in exports, representing a net increase of 5,595 units, underscores a period of stabilization and consolidation. While the headline growth figure appears conservative, a deeper dive into the data reveals a dramatic shift in market dynamics. Maruti Suzuki, the country’s largest carmaker, has effectively decoupled itself from the broader industry trend, reporting double-digit growth and securing a commanding majority of the export market share.
Conversely, established global players such as Hyundai, Nissan, and Volkswagen faced headwinds, reporting declines in their shipment volumes from Indian shores. The period also highlighted the "SUV-ification" of exports, with crossover and off-road models like the Maruti Fronx and Jimny emerging as the primary drivers of international demand.
Chronology of Performance: H1 FY2027
The first half of the fiscal year 2027 was characterized by a steady monthly progression, though it was marked by various external and internal factors.

- Q1 (April–June 2026): The quarter began with a focus on clearing backlogs and ramping up production for new global models. Maruti Suzuki’s decision to prioritize the export of the Fronx to Latin American and Middle Eastern markets began to pay dividends during this window.
- Q2 (July–September 2026): As the domestic festive season approached in India, manufacturers balanced production lines between local demand and export commitments. During this period, the Jimny saw a massive spike in international shipments, nearly catching up to the Fronx in total volume.
- End of H1: By the close of September 2026, the industry recorded a total of 4.51 lakh units shipped, with the top 50 models accounting for a staggering 99.63% of all car exports, indicating a highly concentrated export portfolio.
Supporting Data: Manufacturer and Model Deep Dive
The Maruti Suzuki Hegemony
The most striking revelation from the H1 FY2027 data is the widening gap between Maruti Suzuki and its competitors. The company exported 2,30,576 units, a 12.06% increase over the 2,05,763 units shipped in H1 FY2026. This performance allowed Maruti Suzuki to capture 51.07% of India’s total car exports, up from 46.15% the previous year.
Essentially, every second car leaving an Indian port for foreign markets now carries a Maruti Suzuki badge. This growth of 24,813 units was more than enough to offset the declines seen by other major manufacturers, effectively keeping the national export figure in positive territory.
The Struggles of the "Big Four" Challengers
While Maruti Suzuki thrived, other top-tier manufacturers experienced a contraction:
- Hyundai Motor India: Retained the second spot but saw a 7.57% decline, shipping 92,008 units compared to 99,540 in the previous year.
- Nissan: Witnessed a sharp 20.19% drop, with volumes falling to 30,014 units.
- Volkswagen: Reported a 27.88% decline, shipping 20,201 units.
- Toyota: Declined by 11.66%, ending the half-year with 16,679 units.
Model-Wise Highlights: The SUV Pivot
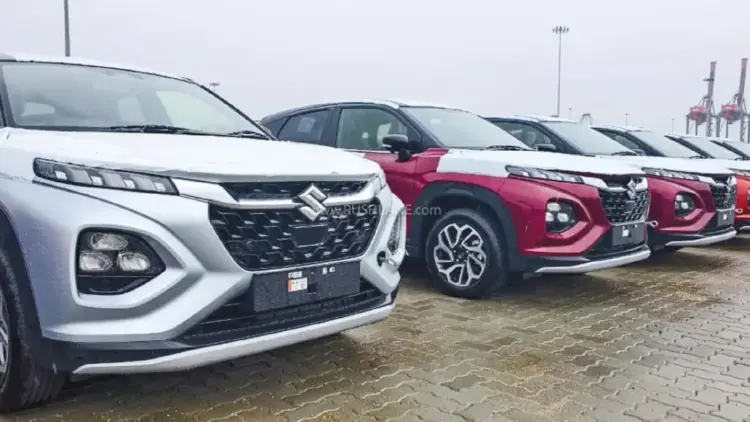
The Maruti Fronx maintained its title as India’s most exported car with 46,147 units. However, the real story lies with the Jimny, which saw a 47.66% surge in exports, reaching 45,183 units. The gap between the Fronx and Jimny has narrowed to less than 1,000 units, suggesting that the rugged off-roader may soon become India’s export leader.
Other notable model performances include:

- Maruti eVitara: Recorded a phenomenal 261.49% growth (21,841 units), signaling a strong international reception for India’s emerging EV and hybrid export capabilities.
- Hyundai Grand i10 Nios: A steady performer in the hatchback segment, growing 10.18% to 29,332 units.
- Tata Tiago: Showcased Tata’s growing export ambitions with a 140% increase in shipments (4,721 units).
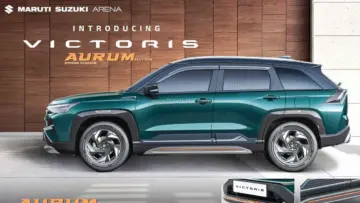
- Victoris: A relatively new entrant in the export charts, it jumped from a negligible base to 10,710 units, representing a strategic push into new territories.
Official Responses and Industry Sentiment
While official statements from the Society of Indian Automobile Manufacturers (SIAM) emphasize the resilience of the sector, industry analysts point toward several factors influencing these numbers.
A spokesperson for Maruti Suzuki attributed their success to a "diversified product portfolio and a strategic focus on emerging markets in Africa, Latin America, and Southeast Asia." The company has aggressively utilized the "Make in India" initiative to position itself as a global production hub for Suzuki’s compact SUV lineup.
In contrast, representatives from companies like Nissan and Volkswagen have hinted at "realigning production schedules" and "addressing supply chain bottlenecks" as reasons for the temporary dip in export volumes. Analysts suggest that some manufacturers are prioritizing the domestic Indian market, which is currently experiencing a much more aggressive growth trajectory than the global export market.
Comparative Analysis: Domestic vs. Export Growth
To understand the 1.25% export growth, it must be viewed in the context of India’s internal automotive boom. In H1 FY2027, domestic car sales surged by 27.16%, reaching 26,36,926 units.
The disparity between domestic growth (27.16%) and export growth (1.25%) suggests that manufacturers are facing a "capacity dilemma." With local demand at an all-time high, several carmakers are likely diverting their production capacities to satisfy Indian consumers, leading to a stagnation in export growth for those without massive excess capacity. Currently, exports account for 14.62% of India’s total automotive production volume (30.88 lakh units), a slight decrease in the ratio compared to the previous year.

Implications for the Future
The data from H1 FY2027 carries several long-term implications for the Indian economy and the global automotive supply chain.
1. Strengthening the "Make in India" Brand
Despite the modest growth percentage, the sheer volume of nearly half a million cars in six months reinforces India’s status as a reliable manufacturing base. The success of the Fronx and Jimny proves that Indian-manufactured vehicles meet the stringent quality and safety standards of diverse international markets.
2. The Rise of Indian Brands Globally
The significant growth of Tata Motors (up 42.62%) and the emergence of models like the eVitara suggest that Indian-origin engineering is gaining traction. As Tata and Mahindra (despite its current dip) expand their global footprint, the "Indian brand" is evolving from a purveyor of budget hatchbacks to a provider of sophisticated SUVs and electric vehicles.
3. Logistical and Geopolitical Considerations
The modest export growth also reflects global economic realities. Fluctuating shipping costs, regional conflicts affecting maritime routes (such as the Red Sea), and varying inflation rates in target markets like Europe and Africa have made the export business more volatile. Manufacturers who have diversified their export destinations—like Maruti Suzuki—have shown better resilience against these localized economic shocks.
4. The EV Transition
The massive growth of the eVitara exports is a precursor to what is expected to be a major shift. As India’s EV infrastructure matures and production scales up, the next few years will likely see electric vehicles taking up a much larger slice of the export pie, potentially revitalizing the growth percentages for manufacturers currently seeing declines in internal combustion engine (ICE) shipments.

Conclusion
The H1 FY2027 car export data paints a picture of an industry at a crossroads. While Maruti Suzuki’s dominance provides a stable foundation, the decline in exports from other major players highlights the intense competition and the pull of a burgeoning domestic market. However, with a net growth of 1.25% and a total volume exceeding 4.5 lakh units, India remains a formidable force in the global automotive trade. As manufacturers continue to pivot toward SUVs and electric powertrains, the second half of the fiscal year will be a critical period to see if the industry can accelerate its export momentum to match its domestic success.