Introduction
As the global community prepares for the 31st United Nations Climate Change Conference (COP31) in Antalya, Turkey, India finds itself at a critical crossroads. Despite exceeding its initial climate commitments years ahead of schedule, the nation’s power grid is experiencing unprecedented strain. In September, a month traditionally marking the end of the summer peak, India successfully met a daytime demand of over 267 GW. However, as the sun set and solar generation tapered off, the system buckled under a deficit of more than 7.7 GW.
This "after-sunset" shortfall underscores the central challenge of India’s energy transition: balancing rapid decarbonization with the unrelenting demand of a growing economy. With the recent submission of its 2035 Nationally Determined Contribution (NDC), India has raised the bar, targeting a 60% non-fossil installed capacity by 2035. This ambitious goal is not merely a climate pledge but a complex navigational exercise through geopolitical volatility, economic fluctuations, and technological shifts.
Main Facts: The 2035 Mandate and the Current Landscape
India’s climate strategy is increasingly anchored in the power sector, which is expected to be the primary engine of the country’s transition over the next decade. The core of this strategy is the updated NDC, which pivots from the successful 2030 goals to a more rigorous 2035 framework.
The 60% Target
The headline figure of India’s new climate roadmap is the commitment to reach 60% non-fossil fuel-based electricity generation capacity by 2035. This includes solar, wind, nuclear, large hydro, and biomass. Currently, India stands at approximately 54% non-fossil capacity, having already achieved its 2030 target of 50% five years ahead of schedule.
The Solar Gap and Reliability
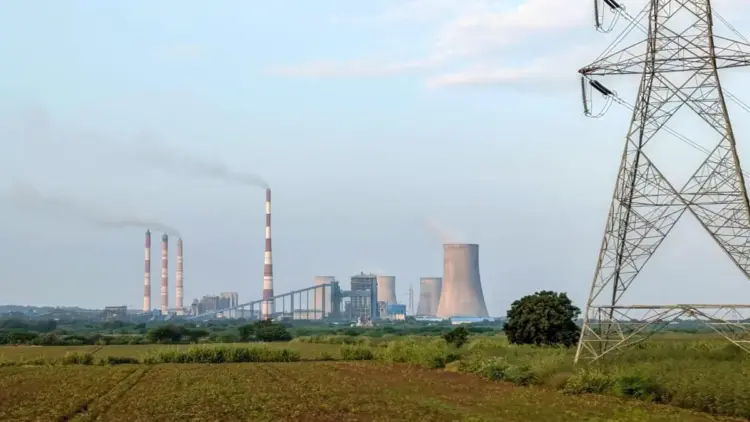
While the capacity numbers look promising, the operational reality is more nuanced. The 7.7 GW shortfall recorded in September highlights the "intermittency gap." India’s massive solar installations provide ample power during the day, but the lack of adequate storage—such as Battery Energy Storage Systems (BESS) or Pumped Hydro Storage—means the grid remains heavily dependent on thermal (coal) power to bridge the gap during non-solar hours.
Analysis by CEEW
Research by the Council on Energy, Environment and Water (CEEW) suggests that India’s non-fossil share could actually land anywhere between 60% and 68% by 2035. This eight-percentage-point variance depends on several "swing factors," including GDP growth rates, the success of domestic manufacturing, and the pace of global technological cost reductions.

Chronology: From 2030 Success to 2035 Ambition
2015–2021: The Foundations
Following the Paris Agreement, India set a target of 40% non-fossil capacity by 2030. Rapid scaling of solar auctions and the "One Sun, One World, One Grid" initiative characterized this period.
2022–2024: Accelerated Achievement
India revised its 2030 target upward to 50% at COP26 in Glasgow. Remarkably, by late 2023 and early 2024, the country reached the 50% milestone, driven by record-breaking renewable energy additions and a revitalization of the nuclear and large hydro sectors.
September 2024: The Reality Check
Despite the capacity growth, a late-season heatwave and industrial surge in September 2024 pushed daytime demand to 267 GW. The subsequent evening shortfall of 7.7 GW forced the Ministry of Power to tap into captive thermal plants and explore emergency measures, highlighting the fragility of a solar-heavy grid without storage.
November 2024: COP31 and the 2035 NDC
As COP31 opens in Antalya on November 9, India’s 2035 NDC becomes the official benchmark. This marks the first time India has submitted a mid-term target that accounts for the post-2030 landscape, signaling a shift from "catching up" to "leading the curve."
Supporting Data: The Drivers of Uncertainty
The feasibility of the 60% target is tethered to three primary variables: economic growth, demand-side behavior, and supply-side costs.
1. The GDP Correlation
The demand for electricity is inextricably linked to India’s economic trajectory. CEEW projections illustrate a stark divide:

- High-Growth Scenario: If India maintains an average GDP growth of 7.6% through 2035, driven by a surge in manufacturing, power demand is expected to hit 3,025 billion units (BU).
- Low-Growth Scenario: If global conflicts and trade disputes slow growth to 5.9%, demand drops to 2,567 BU.
This difference of 458 billion units is significant. A slump in demand reduces the appetite for new investments, potentially slowing the installation of new renewable plants and leaving the country with a higher-than-anticipated reliance on existing fossil fuel assets.
2. Behavioral Shifts (Mission LiFE)
The Indian government’s "Lifestyle for Environment" (LiFE) initiative aims to reduce consumption through behavioral change. For instance, increasing the default temperature of air conditioners from 20°C to 24°C across the country could significantly flatten peak demand. While this is a victory for efficiency, it creates a "policy tension": if demand is successfully moderated, the commercial incentive to build massive new green energy parks may diminish, paradoxically making the percentage-based 60% target harder to reach as the total "pie" of capacity stops growing.
3. Supply-Side Constraints and Import Duties
India’s solar ambitions are currently caught between the desire for energy independence and the need for low-cost components.
- Cost Sensitivity: If import duties on solar modules remain high to protect domestic manufacturers, the price of solar electricity could rise from ₹2.5/kWh to ₹3.0/kWh.
- Investment Impact: Even a small increase in per-unit cost can reduce the Internal Rate of Return (IRR) for investors, leading to a slowdown in grid additions.
Official Responses and Policy Frameworks
The Indian government and various state agencies have responded to these challenges with a mix of protectionist trade policies and aggressive domestic incentives.
The Ministry of Power’s Strategy
In response to the September shortages, the Ministry of Power has accelerated the "Resource Adequacy" framework, requiring Discoms (Distribution Companies) to contract enough capacity to meet peak demand years in advance. There is also a renewed push to bring older thermal plants back online or extend their lives to ensure grid stability during non-solar hours.
Promoting Low-Carbon Technology
Beyond solar and wind, the official stance has shifted toward a "diversified green" portfolio. This includes:

- Nuclear Expansion: Significant investment in Small Modular Reactors (SMRs) and the completion of large-scale plants like Kudankulam.
- Green Hydrogen: The National Green Hydrogen Mission aims to decarbonize heavy industry, which will eventually create a massive new "base load" for renewable energy.
- Carbon Capture: Early-stage policy discussions are underway to integrate Carbon Capture and Storage (CCS) with remaining coal plants.
Mission LiFE
The Prime Minister’s office continues to champion Mission LiFE on global stages, positioning it as India’s unique contribution to climate mitigation. By focusing on "pro-planet people," the government hopes to decouple economic growth from carbon-intensive consumption patterns.
Implications: A Global and Domestic Balancing Act
Geopolitical Risks and Energy Security
The ongoing volatility in West Asia and the resulting fluctuations in oil and gas prices present both a threat and an opportunity. High fossil fuel prices act as a "natural tax" that could accelerate the electrification of transport (EVs) and cooking. However, geopolitical shocks also disrupt the supply chains for critical minerals—lithium, cobalt, and rare earth elements—essential for the batteries needed to solve India’s 7.7 GW sunset gap.
The 1.5°C Threshold
The UNEP’s recent Emissions Gap Report warns that the world is on track to breach the 1.5°C warming threshold within years. For India, a country highly vulnerable to heatwaves and erratic monsoons, the margin of this breach is catastrophic. The 2035 NDC is therefore not just a diplomatic document but a survival strategy. If India fails to decarbonize its grid while simultaneously electrifying its economy, it risks a "double failure": failing to meet climate goals while suffering the economic brunt of climate impacts.
The Role of COP31
COP31 in Antalya will be a test of India’s leadership. The presidency is expected to push for a global target regarding the share of electricity in final energy use. India is well-positioned to lead this conversation, but its credibility will depend on its ability to prove that a large, developing economy can decarbonize its grid even while navigating the "polycrisis" of trade wars, energy inflation, and the massive power requirements of emerging technologies like Artificial Intelligence.
Conclusion
India’s path to 60% non-fossil capacity by 2035 is paved with both promise and peril. The nation has proven it can build capacity at a record pace, but the next decade requires more than just installation; it requires integration. Navigating the uncertainties of GDP growth, managing the costs of domestic manufacturing, and solving the storage puzzle are the prerequisites for success. As the sun sets on the 2030 goals, the focus shifts to a 2035 horizon where energy security and climate ambition must finally become one and the same.