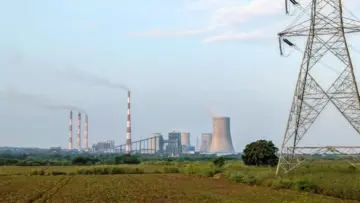
New Delhi — As the sweltering heat of the summer peak fades into the rearview mirror, India’s power infrastructure remains under an unprecedented level of duress. Even in September, traditionally a month of cooling temperatures, the national grid met a staggering daytime demand of over 267 gigawatts (GW). However, the onset of dusk reveals a persistent structural vulnerability: as solar generation tapers off with the setting sun, the country faces a deficit of more than 7.7 GW.
This "post-sunset gap" serves as a sobering backdrop to India’s latest international climate commitments. While New Delhi recently withdrew its bid to host the COP33 summit in 2028, its focus has shifted toward the immediate future. COP31, scheduled to open in Antalya on November 9, will mark the first United Nations climate summit since India submitted its 2035 Nationally Determined Contribution (NDC). This new roadmap significantly raises the bar for the world’s most populous nation, targeting a 60% non-fossil fuel installed capacity by 2035.
The transition is no longer a matter of environmental altruism but a strategic necessity. With the United Nations Environment Programme (UNEP) warning that the world is likely to breach the 1.5°C warming threshold within years, India finds itself at a crossroads where economic growth, energy security, and climate mitigation must be reconciled under conditions of extreme global volatility.
Main Facts: The 2035 NDC and the Power Sector Pivot
India’s updated NDC for 2035 represents a bold evolution of its "Panchamrit" (five-fold) strategy first introduced at COP26 in Glasgow. The cornerstone of this updated commitment is the reliance on the power sector to drive the lion’s share of decarbonization.
Current Capacity and Achievement
India has already demonstrated a remarkable ability to over-perform on its initial climate goals. The country achieved its 2030 target of 50% non-fossil fuel capacity five years ahead of schedule. As of late 2024, non-fossil sources—including solar, wind, hydro, and nuclear—account for approximately 54% of the nation’s total installed capacity.
The 60% Target
The move to a 60% target by 2035 is designed to provide a buffer against the unpredictability of the next decade. Unlike previous targets, which were viewed through the lens of pure expansion, the 2035 goal is an exercise in "calibrated ambition." It acknowledges that while the share of renewables must grow, the stability of the grid requires a nuanced mix of storage, base-load nuclear, and flexible thermal backup.

The Solar Shortfall
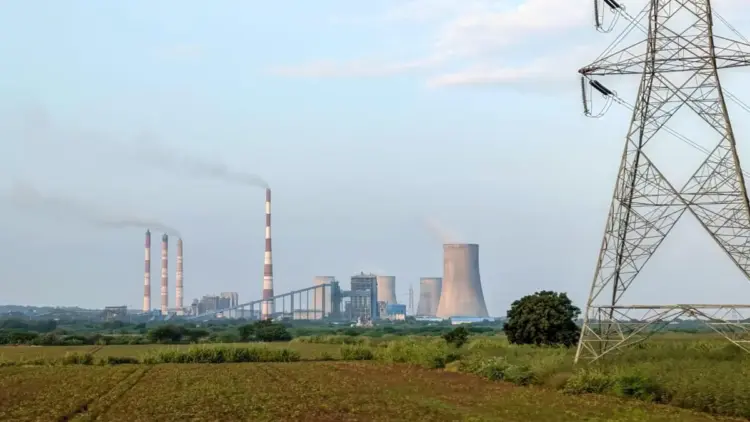
The 7.7 GW deficit experienced after sunset in September highlights the "intermittency challenge." While India is a global leader in solar deployment, the lack of large-scale battery energy storage systems (BESS) and pumped hydro storage means that the country remains heavily reliant on coal and gas to bridge the gap when the sun is not shining.
Chronology: From Paris to Antalya
To understand the weight of the 2035 NDC, one must look at the trajectory of India’s climate diplomacy and domestic energy policy over the last decade.
- 2015 (Paris Agreement): India commits to 40% non-fossil fuel capacity by 2030.
- 2021 (COP26, Glasgow): Prime Minister Narendra Modi announces the "Panchamrit" targets, including reaching 500 GW of non-fossil capacity and a 50% share of renewables by 2030.
- 2022-2023 (The Acceleration): Rapid solar and wind auctions, coupled with policy pushes like the Green Hydrogen Mission, accelerate the transition. India hits the 40% mark and sets its sights on 50%.
- July 2024: Official data confirms India has crossed the 50% non-fossil capacity threshold, five years ahead of the 2030 deadline.
- September 2024: India submits its 2035 NDC to the UNFCCC, formalizing the 60% target and setting the stage for discussions at COP31 in Antalya.
- November 2024 (Antalya): COP31 serves as the first global audit of how major economies like India plan to bridge the gap between "installed capacity" and "actual generation" in a post-1.5°C world.
Supporting Data: The CEEW Projections and Structural Drivers
Analysis by the Council on Energy, Environment and Water (CEEW) suggests that India’s non-fossil capacity share could actually fluctuate between 60% and 68% by 2035. This eight-percentage-point spread is not a margin of error but a reflection of three critical structural drivers: GDP growth, demand-side behavior, and supply-side constraints.
1. The GDP Growth Paradox
Economic growth is the primary driver of electricity demand. CEEW’s high-growth scenario—assuming an average annual GDP growth of 7.6% and a burgeoning manufacturing sector—projects India’s power demand to reach 3,025 billion units by 2035.
However, a lower growth trajectory of 5.9% would reduce that demand to 2,567 billion units. Paradoxically, slower economic growth could hinder the green transition. A shortfall of 458 billion units in demand would reduce the appetite for new investments, potentially slowing the decommissioning of old coal plants and delaying the capital-intensive rollout of new renewable projects.
2. Behavioral Shifts: The LiFE Initiative
The Indian government’s "Lifestyle for Environment" (LiFE) initiative introduces a wildcard into demand forecasting. By promoting behavioral changes—such as setting air conditioners to 24°C or 26°C instead of 18°C—India aims to moderate electricity consumption.

While these measures are vital for sustainability, they create a policy tension. Significant reductions in per-capita consumption can slow the pace of capacity expansion, making it harder for the energy sector to achieve the economies of scale required to further drive down the cost of green technologies.
3. Supply-Side Hurdles and Solar Economics
The cost of solar power in India has historically been among the lowest in the world. However, recent supply-side constraints are threatening this momentum.
- Import Duties: High tariffs on imported solar modules, intended to boost domestic manufacturing (Atmanirbhar Bharat), have temporarily increased the Levelized Cost of Energy (LCOE).
- Price Sensitivity: CEEW notes that if the price of solar electricity rises from ₹2.5/kWh to ₹3/kWh due to duties and supply chain disruptions, the technology’s attractiveness to private investors diminishes, potentially stalling grid additions.
Official Responses and Institutional Outlooks
The Indian government and global financial institutions are already adjusting their strategies to meet these uncertainties.
The Ministry of Power’s Strategy
To combat the non-solar hour shortage, the Ministry of Power has recently tapped into captive thermal plants. By integrating these private industrial power plants into the national grid during peak evening hours, the government is attempting to bridge the 7.7 GW gap without resorting to widespread load-shedding. This move signals that while the long-term goal is green, the short-term priority remains grid stability at any cost—including the temporary use of fossil fuels.
The Goldman Sachs Revision
Global economic headwinds are also playing a role. Goldman Sachs recently revised India’s growth forecast for FY 2026-27 downward to 5.9%, from an earlier projection of 7%. This revision is attributed to geopolitical shocks, particularly the ongoing conflicts in West Asia, which threaten energy prices and global trade routes.
The UNEP Warning
The UNEP’s latest "Emissions Gap Report" emphasizes that the margin by which the world breaches the 1.5°C threshold will determine the severity of climate impacts. For India, this translates to an increased frequency of extreme weather events—heatwaves and floods—which further strain the power grid by creating unpredictable spikes in demand.

Implications: Geopolitics and the Electrification Frontier
The path to 2035 is not merely a domestic infrastructure project; it is a geopolitical navigation exercise. The success of India’s 60% target carries several profound implications for the global energy landscape.
Strategic Autonomy Through Electrification
Rising oil and gas prices, exacerbated by instability in West Asia, present India with a strategic opportunity. By accelerating the electrification of transport (EVs), cooking (induction), and heavy industry, India can reduce its reliance on imported fossil fuels. However, this "electrification of everything" only aids climate goals if the power supply itself is decarbonized. If the grid remains reliant on coal to meet the evening peak, the carbon footprint is merely shifted, not eliminated.
The COP31 "Electric Ambition"
A key theme pushed by the COP31 Presidency in Antalya is the share of electricity in final energy use worldwide. The IPCC’s sixth assessment report highlights that deep decarbonization is impossible without massive electrification. India’s 2035 NDC positions the country as a test case for this theory. If a developing giant can maintain 7% GDP growth while shifting 60% of its massive power capacity to non-fossil sources, it provides a blueprint for the Global South.
The Uncertainty Factor
Ultimately, India’s climate trajectory is highly sensitive to external shocks. Supply chain concentrations—particularly the global reliance on a few nations for critical minerals and solar components—remain a significant risk. For India to reach the more optimistic 68% non-fossil share by 2035, it will require:
- A rapid reduction in the cost of Battery Energy Storage Systems (BESS).
- The successful scaling of small modular nuclear reactors.
- A stable geopolitical environment that allows for the free flow of green technology and capital.
Conclusion
India’s 2035 NDC is a document of "calibrated ambition." It reflects a nation that has matured in its climate response—moving from aspirational promises to a hard-nosed assessment of what is possible in an era of global turbulence. As the delegates gather in Antalya for COP31, the world will be watching to see if India’s plan to decouple economic growth from carbon emissions can withstand the pressures of a strained grid and an uncertain world. The next decade will determine whether the 60% target is a ceiling or a floor for India’s green future.