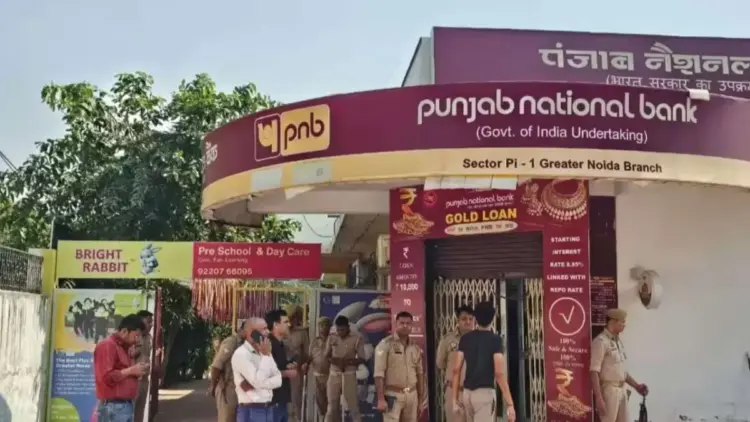
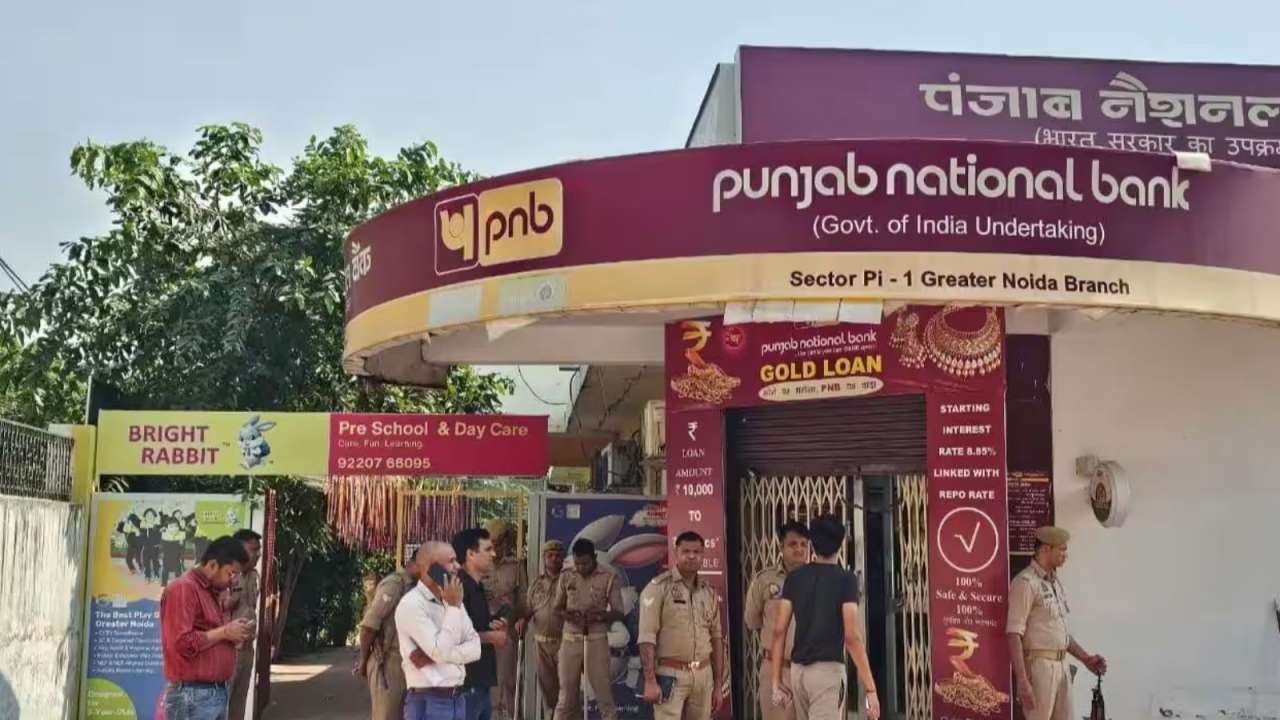
GREATER NOIDA, UTTAR PRADESH – Punjab National Bank (PNB), one of India’s leading public sector banks, finds itself embroiled in a significant controversy following allegations of a multi-crore fraud at its Greater Noida branch. Customers have reported an estimated Rs 35 crore missing from their accounts, prompting swift action from the bank, including the suspension of several staff members and a categorical assurance to honour all genuine claims. The unfolding scandal has cast a shadow over customer confidence and highlighted the persistent challenges of maintaining financial integrity within the banking system.
The allegations, which surfaced recently, detail a sophisticated scheme affecting numerous customers, with funds allegedly siphoned from various financial instruments, including fixed deposits (FDs), savings accounts, and mutual fund investments. In response to the growing concerns, PNB has stated its unwavering commitment to a zero-tolerance policy against fraud and has initiated a thorough investigation, while also working closely with law enforcement authorities to uncover the full extent of the irregularities. So far, the bank has already settled three initial claims amounting to Rs 43 lakh, signalling its intent to address customer grievances promptly.
The Unfolding Scandal: A Deep Dive into PNB’s Greater Noida Fraud
The gravity of the situation became apparent as a growing number of customers from the Greater Noida branch reported discrepancies in their account balances, leading to widespread alarm. The cumulative losses are currently estimated to be around Rs 35 crore, making it a substantial financial irregularity that demands immediate and comprehensive action.
The Genesis of the Allegations: Missing Millions and Mounting Concerns
The initial reports of missing funds began trickling in from individual customers, each discovering unexpected and unauthorized deductions or disappearance of their invested capital. What started as isolated incidents soon coalesced into a larger pattern, suggesting a systemic issue rather than mere administrative errors. The sheer scale of the alleged fraud, encompassing 24 distinct customer accounts and involving a diverse range of financial products, points towards a deeply entrenched problem.
Customers, who had entrusted their hard-earned money to PNB, found themselves in a state of shock and disbelief. The alleged fraud is particularly insidious as it targets a spectrum of financial instruments, indicating a possible internal manipulation of records across different banking operations. Whether it involves the unauthorized premature encashment of fixed deposits, fraudulent withdrawals from savings accounts, or the misdirection of funds intended for mutual fund investments, the common thread remains the alleged breach of trust and financial security.
PNB’s proactive step in settling three initial claims worth Rs 43 lakh serves as an important, albeit preliminary, measure to alleviate immediate customer distress. This action, however, underscores the reality of the losses incurred and the bank’s recognition of its responsibility to affected individuals.
Customer Testimonies: Voices of Distress and Disbelief
The human element of this financial scandal is perhaps the most poignant. Behind the cold figures of missing millions are the stories of individuals whose financial stability and future plans have been jeopardized.
One prominent case involves Shrichand, a customer who claims a staggering Rs 1.16 crore was stolen from his fixed deposit. Fixed deposits are often considered among the safest investment avenues, chosen by individuals seeking stability and guaranteed returns. The alleged siphoning of such a substantial amount from an FD account strikes at the very core of trust in banking instruments. For Shrichand, this loss represents not just a financial setback but potentially the erosion of years of savings and future security.
Another distressing account comes from farmer Bijendra Singh, whose bank balance allegedly plummeted from a substantial Rs 87 lakh to a mere Rs 1 lakh. Such a drastic reduction in funds can have catastrophic consequences, particularly for individuals dependent on these savings for their livelihoods, agricultural operations, or family expenses. The abrupt disappearance of nearly all his funds would undoubtedly leave Bijendra Singh in a precarious financial situation, highlighting the profound impact of such fraudulent activities on ordinary citizens.
These individual cases are illustrative of the broader distress experienced by the 24 customers who have come forward. Beyond the quantifiable financial losses, there is an immeasurable toll on the emotional well-being of the victims. The feeling of betrayal, the anxiety over financial ruin, and the arduous process of seeking redressal can be incredibly draining, often leading to significant psychological stress. The collective voice of these customers underscores the urgency with which PNB and the authorities must act to ensure justice and restitution.
Chronology of Events and Investigative Pathways
The response to the alleged fraud has been multifaceted, involving both internal banking investigations and external law enforcement intervention. A clear timeline of events is crucial to understanding the progression of this complex case.
A Timeline of Discovery and Response
The exact date when customers first noticed their missing funds is not explicitly stated, but it can be inferred that these discrepancies came to light through routine account checks, transaction alerts, or when individuals attempted to access their funds. As more customers identified similar issues, the scale of the problem became undeniable, prompting a collective approach to address their grievances.
Following the mounting complaints, an First Information Report (FIR) was promptly lodged against "unknown bank employees." This crucial legal step signifies the official commencement of a criminal investigation. The FIR has been filed under Section 316(5) of the Bharatiya Nyaya Sanhita (BNS), a provision specifically dealing with criminal breach of trust. This legal classification indicates that the authorities suspect an intentional and fraudulent misappropriation of funds by individuals entrusted with their management.
In parallel with the police investigation, PNB initiated its own rigorous internal inquiry. Recognizing the severity of the allegations and the potential involvement of its own staff, the bank took decisive preliminary action. Several employees, including the branch manager, were swiftly suspended. These suspensions are a standard procedure in such cases, designed to prevent further potential irregularities, ensure the integrity of the investigation, and signal the bank’s serious approach to the matter. PNB’s subsequent public statement, assuring customers of payment for all genuine claims, was a critical move to manage public perception and instill confidence amidst the crisis.
The Legal Framework: Understanding Criminal Breach of Trust
Section 316(5) of the Bharatiya Nyaya Sanhita (BNS), under which the FIR has been filed, pertains to "criminal breach of trust." This legal provision is invoked when a person, being in any manner entrusted with property, or with any dominion over property, dishonestly misappropriates or converts to his own use that property, or dishonestly uses or disposes of that property in violation of any direction of law prescribing the mode in which such trust is to be discharged, or of any legal contract, express or implied, which he has made touching the discharge of such trust, or wilfully suffers any other person so to do.
In the context of a bank fraud, this section is particularly relevant as bank employees are entrusted with the financial assets and confidential information of their customers. Any dishonest act leading to the misappropriation of these funds would fall squarely under this legal definition. The police investigation will now focus on gathering evidence to establish the elements of criminal breach of trust, including the identification of the individuals responsible, their intent, and the means by which the funds were diverted.
It is important to distinguish between the criminal and civil aspects of such a case. While the criminal investigation aims to prosecute the individuals responsible for the fraud, the bank’s assurance to honour genuine claims addresses the civil liability – ensuring the victims are financially compensated. These two tracks often proceed simultaneously, with the criminal proceedings providing a basis for justice and accountability, and the civil actions focusing on restitution.
Supporting Data: The Anatomy of a Banking Fraud
The alleged Rs 35 crore fraud at PNB Greater Noida is a stark reminder of the sophisticated and often internal nature of financial irregularities that can plague banking institutions. Understanding the potential mechanics of such a fraud provides crucial context.
Unpacking the Alleged Modus Operandi
While PNB and the police are still investigating the precise methods used, the nature of the allegations – involving multiple accounts and financial products – suggests a pattern of internal collusion and systematic manipulation. Several potential modus operandi could be at play:
- Internal Collusion: Given the suspension of the branch manager and other employees, internal collusion appears to be a strong possibility. This would involve bank staff actively participating in or facilitating the fraudulent transactions, leveraging their access to customer accounts and internal systems.
- Unauthorized Withdrawals/Transfers: Employees with access to customer accounts might have initiated unauthorized withdrawals, transfers to accomplice accounts, or created fictitious loan accounts to siphon off funds. This often involves bypassing internal controls or creating false documentation.
- Manipulation of Records: For fixed deposits, this could involve prematurely closing FDs without customer consent, fabricating withdrawal slips, or altering maturity instructions to divert funds. For savings accounts, it might involve making ledger entries that do not reflect actual transactions.
- Diversion of Mutual Fund Investments: If customers’ funds were intended for mutual fund investments, the fraud could involve diverting these funds to different, unauthorized accounts instead of the intended investment vehicles, or even making redemption requests without customer knowledge and redirecting the proceeds.
Internal fraud is particularly insidious because it involves individuals who are trusted guardians of public money. Their intimate knowledge of banking procedures and internal controls can be exploited to circumvent security measures, making detection challenging without robust audit mechanisms and vigilant oversight.
The Scale and Scope: A Multi-Instrument Attack
The alleged targeting of FDs, savings accounts, and mutual funds indicates a broad-spectrum approach to the fraud. This multi-instrument attack complicates the investigation but also reveals a potential strategy to maximize gains and diversify the source of illicit funds.
- Fixed Deposits (FDs): FDs are usually locked-in investments. Fraudulent activity here often involves premature liquidation, forging signatures, or misrepresenting account holders’ instructions.
- Savings Accounts: These are dynamic accounts with frequent transactions. Fraud can manifest as unauthorized debit entries, transfers to shell accounts, or the creation of ghost accounts.
- Mutual Funds: Funds invested in mutual funds are managed by asset management companies (AMCs) but often routed through banks. Fraud could involve misdirecting subscription amounts, processing unauthorized redemptions, or manipulating nominee details.
The diversity of affected instruments highlights a potential lack of integrated security protocols or a coordinated effort by the fraudsters to exploit vulnerabilities across different product lines. It underscores the need for banks to ensure consistent and robust security measures across all financial services they offer.
Beyond the Numbers: The Broader Context of Banking Frauds in India
The PNB Greater Noida case, while significant, is not an isolated incident in the Indian banking landscape. The Indian banking sector has, unfortunately, grappled with various forms of financial fraud over the years, ranging from small-scale identity theft to large-scale corporate scams. These incidents continually underscore the critical need for:
- Robust Risk Management Frameworks: Banks must invest in sophisticated fraud detection systems, predictive analytics, and real-time monitoring to identify unusual transaction patterns.
- Strengthened Internal Controls: Regular and unannounced audits, segregation of duties, multi-level authorization for high-value transactions, and mandatory staff rotations are essential to prevent internal collusion.
- Enhanced Employee Due Diligence: Thorough background checks, continuous training on ethical conduct, and clear whistle-blower policies can help mitigate risks associated with insider threats.
While the details of this specific case are still emerging, it adds to the ongoing narrative about the vulnerabilities within the banking system and the continuous arms race between fraudsters and financial institutions. It serves as a stark reminder that customer trust, once eroded, is incredibly difficult to rebuild, and sustained efforts are required to maintain the integrity of the financial ecosystem.
Official Responses and Strategic Reassurance
In the wake of the fraud allegations, PNB has moved swiftly to address the crisis, issuing statements that aim to reassure customers and demonstrate a commitment to accountability and resolution.
PNB’s Resolute Stance: Zero Tolerance and Customer Protection
PNB’s official statement has been unequivocal in its condemnation of the alleged fraud, emphasizing a "zero-tolerance policy for misbehaviour, fraud, and financial irregularities." This strong stance is crucial for a public sector bank, which is often seen as a custodian of public trust. The bank’s assurance that "all genuine claims will be honoured" is the most critical message for affected customers, providing a much-needed guarantee of restitution.
The commitment to taking "stern action" against individuals found accountable signals that the bank will not shy away from prosecuting its own employees if their involvement is proven. This is vital for maintaining internal discipline and deterring future misconduct. Furthermore, the bank’s pledge that "internal controls are being reinforced" indicates a review and upgrade of its security protocols and operational procedures. Reinforcing internal controls typically involves:
- Technological Upgrades: Implementing advanced fraud detection software, AI-driven analytics, and real-time monitoring systems.
- Enhanced Audit Mechanisms: Increasing the frequency and scope of internal and external audits, including forensic audits.
- Staff Training and Awareness: Regular training programs for employees on ethical conduct, fraud prevention, and compliance with regulatory guidelines.
- Process Re-engineering: Reviewing and redesigning transaction approval processes to introduce more checks and balances, especially for high-value transactions or unusual activities.
These measures are not merely reactive but are part of a continuous effort to strengthen the bank’s resilience against evolving fraud tactics.
Collaborative Investigations: Police and Bank Synergies
The investigation into the Greater Noida fraud is a collaborative effort between PNB’s internal vigilance teams and the local police. This synergy is essential for a comprehensive inquiry. The bank’s internal investigation focuses on identifying procedural lapses, system vulnerabilities, and the specific individuals involved within its own hierarchy. This often involves analyzing transaction logs, employee access records, and internal communication.
Concurrently, the police investigation, initiated through the FIR, focuses on the criminal aspects, gathering evidence that can stand up in a court of law. This includes interviewing witnesses, seizing documents, and potentially tracing the flow of fraudulent funds. The cooperation between law enforcement and financial institutions is paramount, as banks possess critical data and expertise, while the police have the authority to conduct criminal investigations and make arrests. This dual-track approach ensures both accountability within the bank and legal justice for the perpetrators.
The Regulatory Watchdog: RBI’s Implicit Role
While the Reserve Bank of India (RBI) has not issued a specific statement regarding this particular incident, its role as the central banking institution and primary regulator of commercial banks in India is implicit and paramount. The RBI maintains constant oversight over the financial health, operational integrity, and customer protection measures of all scheduled commercial banks.
In cases of significant fraud, the RBI typically monitors the situation closely. It may:
- Seek detailed reports: Require PNB to submit comprehensive reports on the nature of the fraud, the investigation’s progress, and the steps being taken to prevent recurrence.
- Conduct special audits: Order its own special audits or inspections of the bank’s systems and controls, particularly those related to fraud detection and prevention.
- Issue directives: If systemic weaknesses are identified, the RBI may issue specific directives to PNB or even the broader banking sector to enhance security, improve customer grievance redressal, or strengthen internal governance.
- Assess impact on financial stability: Evaluate the potential impact of such incidents on the bank’s financial stability and the broader public confidence in the banking system.
The RBI’s overarching objective is to maintain financial stability, protect depositors’ interests, and ensure that banks operate with the highest standards of integrity and prudence. The PNB Greater Noida fraud will undoubtedly be on the RBI’s radar, contributing to its ongoing assessment of the banking sector’s resilience against financial crime.
Implications: Navigating the Aftermath and Future Safeguards
The alleged Rs 35 crore fraud at PNB’s Greater Noida branch carries significant implications, not only for the bank and its immediate customers but also for the broader Indian banking sector and public trust.
Rebuilding Trust: Challenges and Opportunities for PNB
For Punjab National Bank, an institution that has faced high-profile fraud cases in the past, this incident presents a formidable challenge in rebuilding and maintaining public trust. Reputational damage from such events can be severe and long-lasting, impacting customer acquisition, investor confidence, and market perception.
- Reputational Damage: The recurrence of fraud allegations, regardless of scale, can reinforce a perception of vulnerability, making it harder for the bank to attract new customers and retain existing ones.
- Impact on Customer Confidence: Locally, customers at the Greater Noida branch will undoubtedly be wary. More broadly, the incident could erode confidence in public sector banks, prompting customers to reconsider their banking relationships.
- Financial Burden: While the bank has assured payment of genuine claims, these settlements represent a direct financial loss. The costs associated with enhanced security, investigations, and legal proceedings will also add to the financial burden.
- Need for Transparent Communication: PNB has an opportunity to demonstrate leadership by maintaining transparent and consistent communication throughout the investigation and resolution process. Regular updates on the progress of claims and investigative findings can help in managing public expectations and rebuilding trust.
Empowering Customers: Vigilance as the First Line of Defence
This incident serves as a critical reminder for all bank customers about the importance of vigilance and proactive financial management. While banks are responsible for securing funds, customers also play a vital role in protecting themselves.
- Regular Account Statement Checks: Customers should routinely check their bank statements, passbooks, and online transaction histories for any unauthorized or suspicious activity. Discrepancies should be reported immediately.
- Safeguarding Personal Financial Information: Never share OTPs, PINs, passwords, or account details with anyone, even if they claim to be from the bank. Bank employees will never ask for such sensitive information over the phone or email.
- Awareness of Fraudulent Tactics: While this case involves internal fraud, customers should also be aware of external threats like phishing, vishing, and social engineering scams that aim to trick them into divulging information.
- Knowledge of Grievance Redressal Mechanisms: Customers should be aware of the channels available for reporting fraud and seeking redressal, including the bank’s internal grievance cell, the Banking Ombudsman scheme, and consumer courts. Prompt reporting is crucial for faster resolution.
The Broader Sectoral Impact: Lessons for Indian Banking
The PNB Greater Noida fraud underscores several critical lessons for the entire Indian banking sector:
- Continuous Technological Upgrades: As fraudsters become more sophisticated, banks must continually invest in and update their fraud detection and prevention technologies. This includes AI-driven analytics, biometric authentication, and robust cybersecurity frameworks.
- Importance of Ethical Conduct and Strong Corporate Governance: The alleged involvement of bank staff highlights the need for a strong ethical culture within financial institutions. Robust corporate governance, strict codes of conduct, and effective whistle-blower protection mechanisms are essential to foster an environment of integrity.
- Balancing Growth and Security in a Digitizing Economy: India’s rapid push towards digital banking offers convenience but also introduces new vulnerabilities. Banks must strike a delicate balance, ensuring that technological advancements are accompanied by equally strong security measures and customer education.
- Call for Stricter Accountability and Faster Justice: The time taken to investigate and prosecute financial fraud can be lengthy. There is a continuous call for streamlining legal processes to ensure quicker justice and deterrent punishments, which can significantly impact the prevalence of such crimes.
Conclusion
The alleged Rs 35 crore fraud at Punjab National Bank’s Greater Noida branch represents a significant challenge for the institution and a stark reminder of the vulnerabilities that persist within the financial system. PNB’s commitment to honouring genuine claims and its swift action against involved staff are crucial first steps in mitigating the damage and rebuilding trust.
As investigations by both the bank and law enforcement proceed, the focus will remain on uncovering the full extent of the fraud, identifying all perpetrators, and ensuring that affected customers receive full restitution. This incident serves as a critical learning opportunity for PNB and the broader Indian banking sector to reinforce internal controls, enhance technological safeguards, and strengthen the ethical fabric of their operations. Ultimately, the stability and integrity of the banking system hinge on its ability to detect, prevent, and decisively respond to such breaches of trust, ensuring the unwavering confidence of its millions of customers.