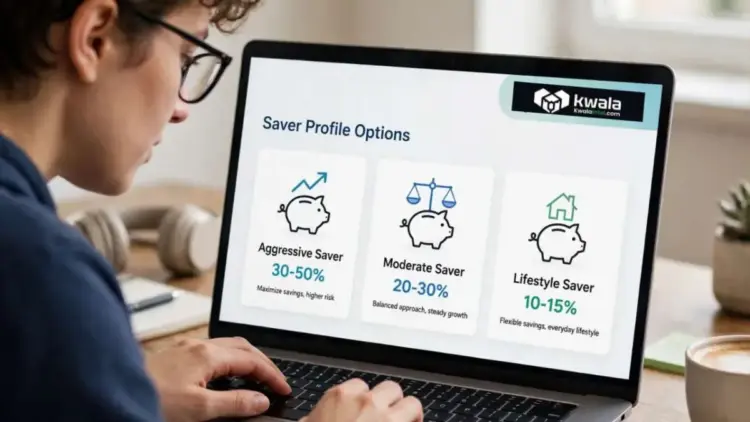
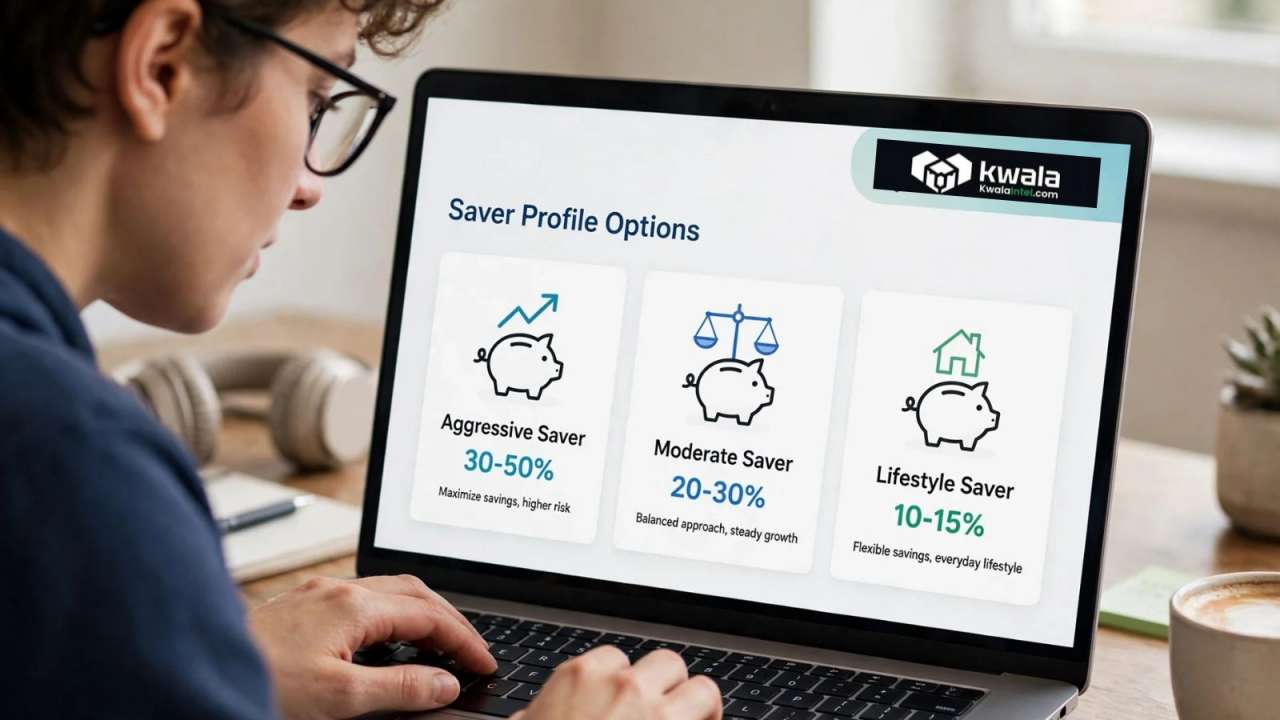
Mumbai, India – In an era where financial stability feels increasingly elusive, the age-old question of "how much should I save?" often yields frustratingly generic answers. However, a new framework from financial intelligence firm Kwala Intel is revolutionizing this conversation, proposing that effective savings strategies are deeply personal, tailored not to income alone, but to an individual’s core financial goals and psychological disposition. Their latest insights categorize savers into three distinct profiles – Aggressive, Moderate, and Lifestyle-Focused – each with a recommended savings percentage range designed to align ambition with action.
According to Kwala Intel, an aggressive saver, driven by the pursuit of early financial independence, should aim to set aside a substantial 30-50% of their income. In contrast, moderate savers, who seek a balanced approach to achieve significant life milestones, are advised to save between 20-30%. For those prioritizing present comfort and experiences, a lifestyle-focused approach suggests a 10-15% savings rate. This nuanced perspective marks a significant departure from conventional, one-size-fits-all financial advice, offering a roadmap that resonates with diverse aspirations and realities.
The Evolution of Financial Prudence: From Generic to Personalized
For decades, financial advice often relied on broad strokes: "save 10% of your income," or "pay yourself first." While these maxims offered a starting point, they frequently failed to account for the intricate tapestry of individual lives, varying income levels, debt burdens, and most critically, personal financial philosophies. The modern financial landscape, characterized by fluctuating markets, rising costs of living, and an increasingly diverse range of investment opportunities, demands a more sophisticated and personalized approach.
The concept of tailoring financial advice to individual needs isn’t entirely new, but Kwala Intel’s framework provides a structured methodology for self-assessment and strategic planning. Historically, financial planning evolved from simple budgeting to complex wealth management, incorporating elements like retirement planning, tax optimization, and estate planning. However, the psychological dimension – why someone saves and what they value – was often an afterthought.
The rise of movements like FIRE (Financial Independence, Retire Early) in the early 21st century highlighted a segment of the population eager to aggressively fast-track their financial goals, pushing savings rates far beyond traditional recommendations. Concurrently, a growing appreciation for work-life balance and experiential living fostered a counter-narrative, where present enjoyment was weighted more heavily against future financial sacrifice. Kwala Intel’s model adeptly captures this spectrum, acknowledging that an individual’s "saver profile" is not static but can evolve with life stages, economic conditions, and changing priorities. Early career professionals might start as aggressive savers, while those approaching mid-career might transition to a moderate stance, and later, perhaps, lean towards a lifestyle-focused approach as major milestones are met. This dynamic perspective underscores the need for regular financial self-assessment, ensuring that one’s saving strategy remains aligned with their evolving life circumstances.
Unpacking the Saver Profiles: A Deeper Dive into Ambition and Strategy
Kwala Intel’s framework is built on a comprehensive understanding of what motivates individuals and how these motivations translate into tangible financial behaviors. Each profile represents a distinct blend of goals, risk tolerance, and lifestyle choices, necessitating a unique financial blueprint.
The Aggressive Saver: Accelerating Towards Financial Independence
The aggressive saver is typically characterized by an unwavering commitment to achieving substantial financial goals, often early financial independence or early retirement. Their primary driver is the rapid accumulation of wealth, allowing them to gain control over their time and choices sooner rather than later.
- Motivations: Freedom from the traditional work structure, building a substantial legacy, achieving specific high-value targets (e.g., launching a business without external funding).
- Strategies: This profile embodies extreme discipline. They adhere to stringent budgeting, meticulously tracking every dollar to maximize savings. They are often adept at finding ways to increase income, whether through side hustles, skill development, or career advancement. Their high savings rate (30-50% of income) necessitates significant sacrifices in present consumption, often foregoing luxuries and prioritizing needs over wants.
- Investment Choices: Aggressive savers typically embrace higher-risk, higher-reward investments. A significant portion of their portfolio, often 70-80% or more, is allocated to equities, including individual stocks, growth-oriented mutual funds, and exchange-traded funds (ETFs). They might also explore alternative investments like real estate (with a focus on appreciation), or even early-stage ventures, understanding the potential for substantial gains, but also the inherent volatility.
- Potential Pitfalls: The intense focus on saving can lead to burnout, feelings of deprivation, or neglecting important social connections. Over-exposure to volatile assets without adequate diversification can also lead to significant losses during market downturns.
- Psychological Traits: Highly disciplined, future-oriented, resilient, and often possessing a strong sense of self-control and delayed gratification.
The Moderate Saver: Navigating the Middle Ground with Purpose
The moderate saver seeks a harmonious balance between enjoying the present and securing the future. Their goals are often specific, measurable life milestones that require substantial capital but don’t necessarily demand the extreme sacrifices of an aggressive approach.

- Motivations: Achieving key life milestones like homeownership, funding children’s education, securing a comfortable retirement, or making significant purchases (e.g., a new car, a large renovation).
- Strategies: Moderate savers practice conscientious budgeting, allowing for a reasonable amount of discretionary spending while consistently hitting their 20-30% savings target. They are pragmatic in their financial decisions, weighing current desires against future needs, and often make trade-offs rather than outright sacrifices.
- Investment Choices: Their portfolio is typically diversified, balancing growth potential with risk mitigation. A common allocation might see 50-70% in equities, complemented by bonds, fixed-income instruments, and potentially real estate. They are comfortable with market fluctuations but seek to mitigate extreme volatility through diversification and regular portfolio reviews.
- Flexibility: This profile often demonstrates greater flexibility in their financial plan, capable of adjusting savings rates or investment strategies in response to life events (e.g., marriage, parenthood, career change).
- Psychological Traits: Balanced, pragmatic, patient, and able to find contentment in both present experiences and future security.
The Lifestyle-Focused Saver: Prioritizing Present Experiences
The lifestyle-focused saver prioritizes present comfort, experiences, and immediate gratification. While they understand the importance of saving, their approach is less about aggressive wealth accumulation and more about ensuring a baseline of financial security without significant disruption to their current way of life.
- Motivations: Enjoying travel, dining out, hobbies, and generally living a comfortable life in the present. Minimizing financial stress in daily life.
- Strategies: This profile aims for a more relaxed approach to budgeting, integrating savings (10-15%) into their existing spending patterns rather than drastically cutting back. They might choose experiences over large material possessions and are often willing to make smaller, consistent contributions to savings rather than large, infrequent ones.
- Investment Choices: Their investment strategy tends to be more conservative, often favoring lower-risk options like fixed deposits, bonds, or balanced mutual funds. While they might have some exposure to equities, it’s typically a smaller percentage (e.g., 30-40%) and focused on stable, dividend-paying companies rather than high-growth, speculative ventures.
- Potential Risks: The primary risk for lifestyle-focused savers is slower wealth accumulation, which can lead to insufficient funds for major life events or retirement, especially when compounded by inflation. They may be more vulnerable to unexpected financial shocks if their emergency fund is not robust.
- Psychological Traits: Present-oriented, experiential, less concerned with long-term financial metrics, and values comfort and immediate enjoyment.
Identifying Your Financial DNA: Beyond Percentages
Determining your saver profile involves more than just selecting a percentage. Kwala Intel advises a deep introspection into your primary financial goals and an honest assessment of your risk tolerance.

The Crucial Role of Primary Goals
- Early Financial Freedom: If your ultimate aspiration is to decouple your income from your time as quickly as possible, allowing you to pursue passions without financial constraint, you likely lean towards the aggressive saver profile. This goal requires significant upfront sacrifice and a long-term vision.
- Meeting Mid-Term Milestones: If your focus is on achieving specific goals within a 5-15 year horizon – such as purchasing a home, funding higher education, or starting a family – a moderate approach that balances saving with current quality of life is probably more suitable.
- Desire for Daily Comfort: If your primary objective is to maintain your current lifestyle, enjoy experiences, and avoid feeling deprived in the present, then a lifestyle-focused saving strategy aligns with your values. This doesn’t mean neglecting the future entirely, but rather finding a sustainable minimum.
Assessing Your Risk Tolerance
Risk tolerance is a critical, yet often overlooked, component of financial planning. It’s not just about what the market can do, but what you can psychologically handle.
- Market Fluctuations: How would you react to a significant market downturn (e.g., 20-30% drop)? An aggressive saver might view this as a buying opportunity, while a lifestyle-focused saver might panic and sell, locking in losses. Your emotional response to volatility is a key indicator.
- Locking Away Income: How comfortable are you with committing a substantial portion of your income to long-term investments, knowing that it won’t be readily accessible for years? An aggressive saver thrives on this commitment, viewing it as progress, whereas a lifestyle-focused saver might feel constrained.
- Practical Tools: Financial advisors often use questionnaires to gauge risk tolerance, asking about hypothetical investment scenarios and personal preferences regarding gains versus losses. These tools, combined with self-reflection, can provide clarity.
The Pillars of Prudent Financial Planning
Regardless of your saver profile, certain foundational principles remain universal for sound financial health. Kwala Intel underscores the importance of these elements before diving into specific savings percentages or investment strategies.

Laying the Foundation: Debt Management and Emergency Funds
Before any significant investment, two critical steps must be addressed:
- Eliminating High-Interest Debt: Debts like credit card balances or personal loans carry exorbitant interest rates that can quickly erode any investment gains. Paying these off should be a top priority, as the guaranteed "return" of avoiding high interest often surpasses typical market returns.
- Accumulating an Emergency Fund: This is your financial safety net, typically 3-6 months’ worth of essential living expenses, held in an easily accessible, liquid account (e.g., a high-yield savings account). It protects you from unexpected job loss, medical emergencies, or unforeseen expenses, preventing you from dipping into long-term investments or incurring new debt.
Strategic Asset Allocation: Matching Investments to Your Horizon
Once the foundation is secure, asset allocation becomes paramount. This refers to how your investment portfolio is divided among different asset classes, such as stocks (equities), bonds (fixed income), and cash equivalents. The choice depends heavily on your time horizon – when you anticipate needing the money.

- Equity for Long-Term Growth: When your objective is years, or even decades, away (e.g., retirement planning for an aggressive or moderate saver), equities are generally beneficial. Historically, stocks have provided the highest returns over long periods, making them an excellent tool to outpace inflation and achieve significant wealth growth. However, they come with higher short-term volatility.
- Safer, More Liquid Choices for Short-Term Needs: For funds that will be needed in a few years (e.g., a down payment on a house, or a child’s college tuition in 3-5 years), equity is risky. Markets can decline unexpectedly, and you might be forced to sell at a loss. Therefore, these funds should be invested in safer, more liquid options like high-yield savings accounts, money market funds, or short-term bond funds, which prioritize capital preservation over aggressive growth.
- Tailoring Allocation to Your Profile:
- Aggressive Savers: Might have 80-90% in equities, potentially including international stocks and growth sectors, with a small allocation to bonds for minimal diversification.
- Moderate Savers: Typically employ a balanced portfolio, perhaps 60-70% in equities (a mix of growth and value), 20-30% in bonds, and some cash.
- Lifestyle-Focused Savers: Might opt for a more conservative allocation, possibly 30-40% in equities (focused on stable, dividend-paying companies), 50-60% in bonds and fixed deposits, and a higher cash reserve.
The Silent Erosion: Battling Inflation
Inflation is often dubbed a "silent tax" because it steadily erodes the purchasing power of money over time. Kwala Intel warns that over 15 years, inflation can significantly reduce the real value of cash and fixed-income investments.
- Real vs. Nominal Returns: Your nominal return is the stated return on your investment. Your real return is the nominal return minus the inflation rate. If your investment yields 5% and inflation is 3%, your real return is only 2%.
- Impact on Different Savers:
- A lifestyle-focused saver with a significant portion of their assets in cash or low-yielding fixed income, especially if also carrying high-interest debt, faces low or even negative real returns. Their purchasing power diminishes year after year.
- An aggressive saver, with a higher allocation to equities (e.g., 80%), has a significantly better chance to beat inflation and grow their real wealth. Equities have historically provided returns that outpace inflation, protecting purchasing power over the long run.
- Importance of Growth: To truly build wealth and maintain future purchasing power, especially for long-term goals, investments must generate returns that comfortably exceed the rate of inflation.
The Art of Rebalancing: Staying on Track
Asset allocation isn’t a set-it-and-forget-it strategy. Over time, market movements can cause your portfolio’s allocation to drift from your target. Rebalancing involves periodically adjusting your portfolio back to your desired allocation by selling assets that have performed well and buying those that have lagged. This ensures your risk level remains consistent with your profile and time horizon. Regular rebalancing (e.g., annually or semi-annually) is crucial for maintaining a disciplined investment approach.

Official Responses: The Consensus on Personalized Financial Guidance
Kwala Intel’s framework resonates deeply with the broader financial planning industry’s growing emphasis on personalized advice. While specific percentages may vary slightly among different firms, the underlying principle – that financial strategies must align with individual goals, risk tolerance, and life circumstances – is a widely accepted consensus.
Financial advisors increasingly act as guides, helping clients articulate their financial aspirations, understand their behavioral biases, and construct tailored plans. The "official response" from the financial community is a strong endorsement of such individualized approaches, moving away from generic advice that often leaves individuals feeling either overwhelmed or unmotivated. Furthermore, financial literacy initiatives, often supported by regulatory bodies, aim to empower individuals to understand these nuances, make informed decisions, and proactively manage their financial futures. The insights from Kwala Intel provide a valuable tool in this endeavor, simplifying complex financial decisions into understandable profiles.

The Far-Reaching Impact of Tailored Saving Strategies
The implications of adopting a personalized saving strategy extend far beyond an individual’s bank account, touching upon their overall well-being and even the broader economy.
For the Individual: A Path to Financial Well-being
- Empowerment and Clarity: Understanding one’s saver profile provides clarity and a sense of direction, transforming the daunting task of saving into a manageable, goal-oriented process. This clarity reduces financial anxiety and fosters greater confidence.
- Goal Achievement: When savings align with deeply held personal goals, the motivation to stick to the plan increases significantly, making the achievement of financial milestones more probable.
- Reduced Stress: A well-defined and personalized financial plan acts as a buffer against life’s uncertainties, reducing stress associated with money matters and contributing to overall mental well-being.
- Adaptability: Recognizing that one’s saver profile can change over time encourages periodic review and adjustment, ensuring the financial plan remains relevant through different life stages and economic shifts.
Broader Economic Implications
On a macro level, aggregate saving rates within a population have significant economic implications. A nation with a healthy saving culture contributes to greater capital formation, which can be channeled into productive investments, fostering economic growth and stability. A balance between consumer spending (which drives demand) and saving (which provides capital) is crucial for a thriving economy. Moreover, robust individual savings reduce reliance on social safety nets in retirement, strengthening national financial resilience.

Embracing the Dynamic Nature of Your Saver Profile
Perhaps the most crucial implication of Kwala Intel’s framework is the understanding that one’s saver profile is not a permanent label. Life happens. A young aggressive saver might become a moderate saver after starting a family, prioritizing stability and specific milestones. Conversely, a lifestyle-focused saver might experience a "financial awakening" and decide to become more aggressive to catch up on retirement savings.
Regularly assessing your primary goals, re-evaluating your risk tolerance, and reviewing your financial plan (at least annually, or after significant life events) is paramount. This dynamic approach ensures that your financial strategy remains a living document, always serving your current aspirations and circumstances.

In conclusion, Kwala Intel’s segmentation of savers offers a powerful lens through which individuals can view their financial journey. By moving beyond generic advice and embracing a personalized strategy, individuals are better equipped to navigate the complexities of wealth accumulation, align their finances with their deepest desires, and ultimately, build a more secure and fulfilling future. The time for one-size-fits-all financial advice is over; the era of personalized financial DNA has arrived.